Productiv · Labor & Logistics Indicatorsgetproductiv.com/insights/labor-logistics-indicators/2026-11
Labor & Logistics Indicators · November 2026
Index 137.8, Warehouse Prices 80.7: Storage Is the Peak Squeeze
Inventories are building faster than storage is opening up, diesel is up 68% from a year ago, and both big parcel carriers set 5.9% increases. Space and freight, not hiring, are the costs to watch into peak.
By Paul Baker, CFO · Published · Data as of Nov. 4, 2026
The Executive Soundbite
Inventories are building faster than warehouse space is opening up. The Logistics Managers' Index shows inventory levels at 66.9 in October, warehousing capacity contracting at 43.5 and warehousing prices at 80.7, their fastest growth since May 2022. Diesel is $6.292/gal, up 68% from a year ago, and UPS and FedEx have both set 5.9% average rate increases. Hiring is not the constraint this peak. Space, fuel and parcel rates are.
“Everyone is budgeting for freight this peak, but storage is the cost moving now. Warehouse prices are growing at the fastest pace since May 2022, and warehouse capacity is shrinking. Inventory is arriving faster than space is opening up. The shipper who plans storage last will pay the most for it.”
The Productiv Labor & Logistics Pressure Index
September 2026 (final)
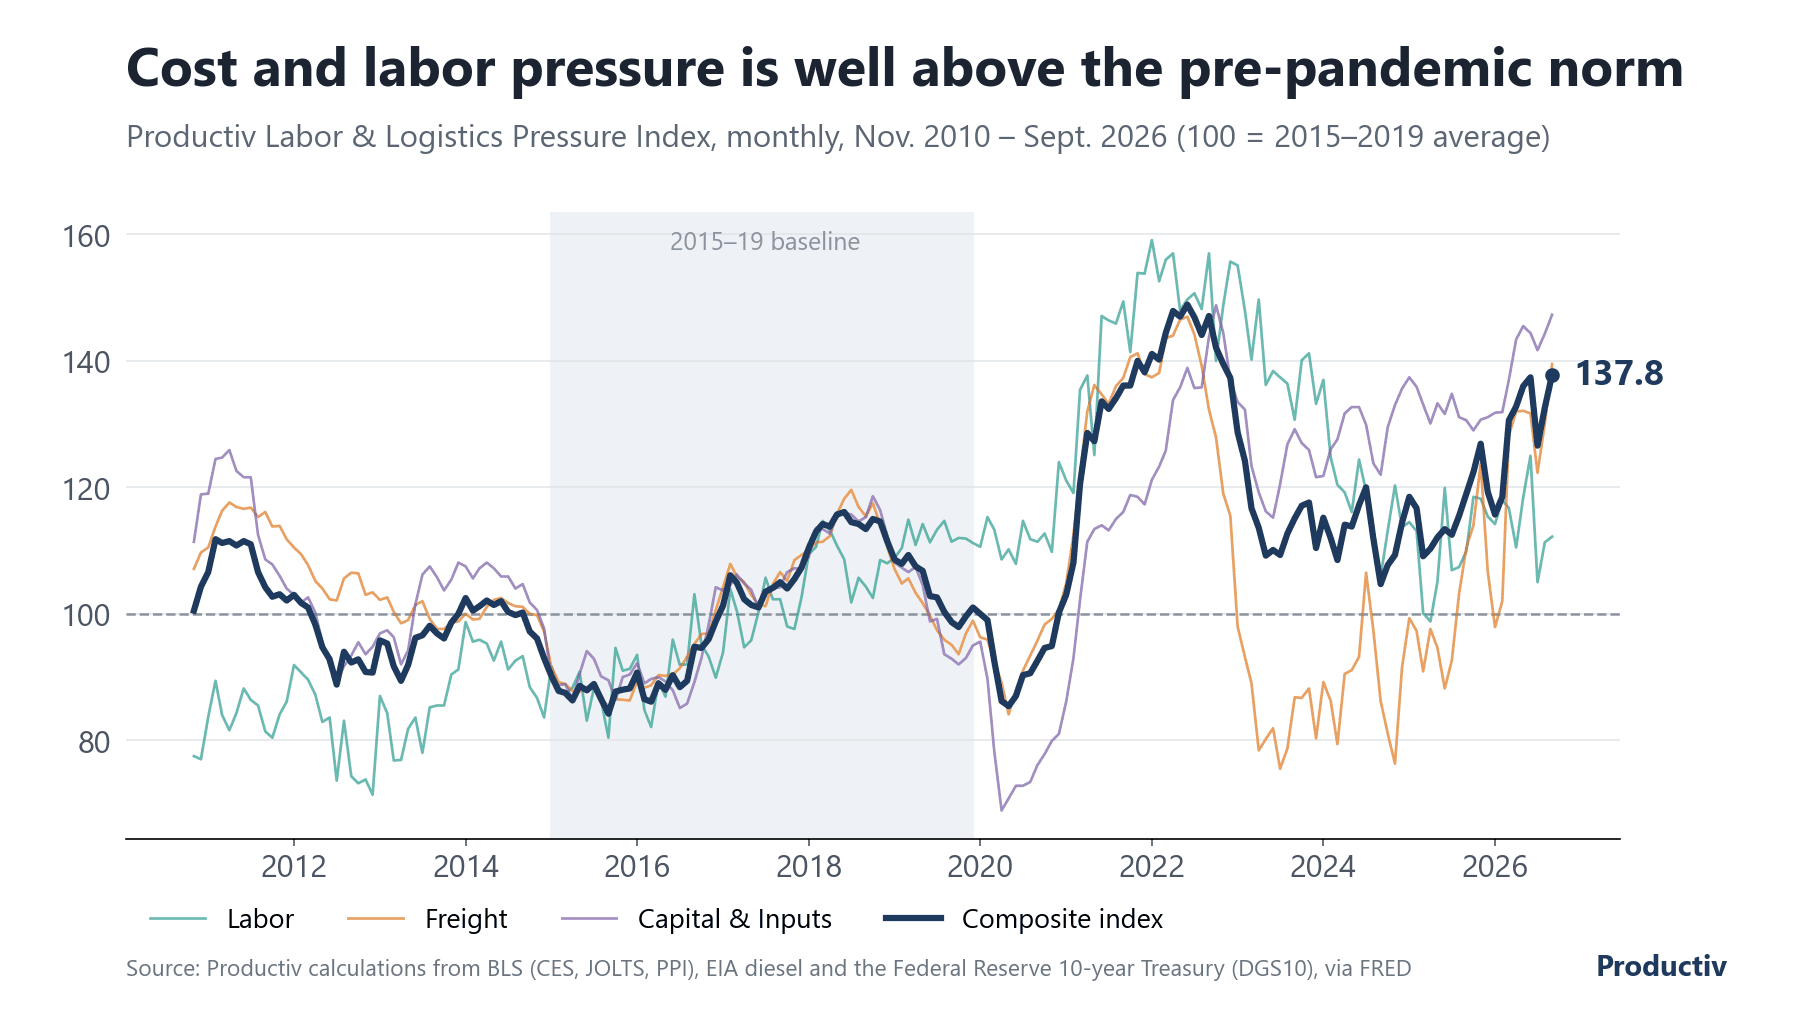
137.8
+5.2 pts m/m · +18.8 pts y/y
- Labor
- 112.2
- Freight
- 139.5
- Capital & Inputs
- 147.3
How to read it: 100 = the 2015–2019 average; every 10 points is one normal-year swing; higher = more cost and labor pressure.
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/00-pressure-index.csv
Chart data (table)
| Month | Index | Labor | Freight | Capital & Inputs |
|---|---|---|---|---|
| Oct. 2024 | 107.7 | 113.1 | 81.1 | 129.5 |
| Nov. 2024 | 109.3 | 120.3 | 76.3 | 133.0 |
| Dec. 2024 | 114.4 | 113.7 | 91.5 | 135.6 |
| Jan. 2025 | 118.5 | 114.5 | 99.3 | 137.4 |
| Feb. 2025 | 116.7 | 113.1 | 97.3 | 135.9 |
| March 2025 | 109.1 | 100.1 | 90.9 | 133.1 |
| April 2025 | 110.3 | 98.8 | 97.6 | 130.1 |
| May 2025 | 112.1 | 105.1 | 94.6 | 133.3 |
| June 2025 | 113.4 | 119.9 | 88.2 | 131.6 |
| July 2025 | 112.5 | 106.9 | 92.6 | 134.8 |
| Aug. 2025 | 115.5 | 107.4 | 103.2 | 131.1 |
| Sept. 2025 | 119.0 | 109.9 | 110.5 | 130.6 |
| Oct. 2025 | 122.4 | 118.5 | 114.0 | 129.0 |
| Nov. 2025 | 126.9 | 118.2 | 123.8 | 130.7 |
| Dec. 2025 | 119.3 | 115.4 | 106.7 | 131.1 |
| Jan. 2026 | 115.7 | 114.2 | 97.9 | 131.8 |
| Feb. 2026 | 118.5 | 118.0 | 102.0 | 131.9 |
| March 2026 | 130.6 | 116.7 | 128.2 | 137.0 |
| April 2026 | 132.8 | 110.5 | 132.0 | 143.4 |
| May 2026 | 136.0 | 118.4 | 132.1 | 145.5 |
| June 2026 | 137.4 | 125.0 | 131.7 | 144.4 |
| July 2026 | 126.6 | 105.0 | 122.3 | 141.7 |
| Aug. 2026 | 132.6 | 111.3 | 130.1 | 144.3 |
| Sept. 2026 | 137.8 | 112.2 | 139.5 | 147.3 |
Full monthly history since Nov. 2010, with each component's raw value, transform and z-score, is in the CSV.
Download CSV DataFor shippers & manufacturing leaders: At 137.8 for September, the index is 18.8 points above a year earlier and at its highest since late 2022, with Capital & Inputs (147.3) and Freight (139.5) doing most of the lifting. Build 2027 budgets on cost growth, not volume.
For 3PLs & facility operators: Labor rose to 112.2 but is still the calmest pillar. Freight jumped to 139.5 as diesel and truckload prices climbed, so fuel and freight pass-through terms matter more this quarter than wage plans.
How the index is built: components, weights, baseline and revision policy
Revision: each issue recomputes the full history from the latest public data. BLS revised August's JOLTS quits rate (2.0% to 2.3%) and openings rate (4.7% to 4.6%) and August producer prices, so August's reading moved from 130.4 to 132.6 (Labor 106.8 to 111.3, Freight 128.6 to 130.1, Capital & Inputs 143.7 to 144.3). The October issue is unchanged.
At a glance
- Storage: The LMI Warehousing Prices index was 80.7 in October 2026, its fastest growth since May 2022, while Warehousing Capacity contracted at 43.5 (Logistics Managers' Index).
- Fuel: U.S. diesel averaged $6.292/gal for the week of Nov. 2, 2026, up $2.539 from a year earlier (EIA).
- Pay: Transportation and warehousing average hourly earnings rose 3.1% year over year in September 2026, behind September CPI inflation of 3.7% (BLS).
- Input prices: Producer prices for final demand rose 6.3% year over year in September 2026 (BLS), and the ISM manufacturing prices index was 75.2 in October (ISM).
- Parcel: UPS (Dec. 21, 2026) and FedEx (Jan. 4, 2027) both set average rate increases of 5.9%. Ground fuel surcharges were 30.25% (UPS) and 29.25% (FedEx) for the week of Nov. 2 (carrier notices).
1. Economy
- Real GDP: +3.4% annualized in Q3 2026 (BEA advance estimate, released Oct. 29), up from +2.2% in Q2. The second estimate is due Nov. 25.
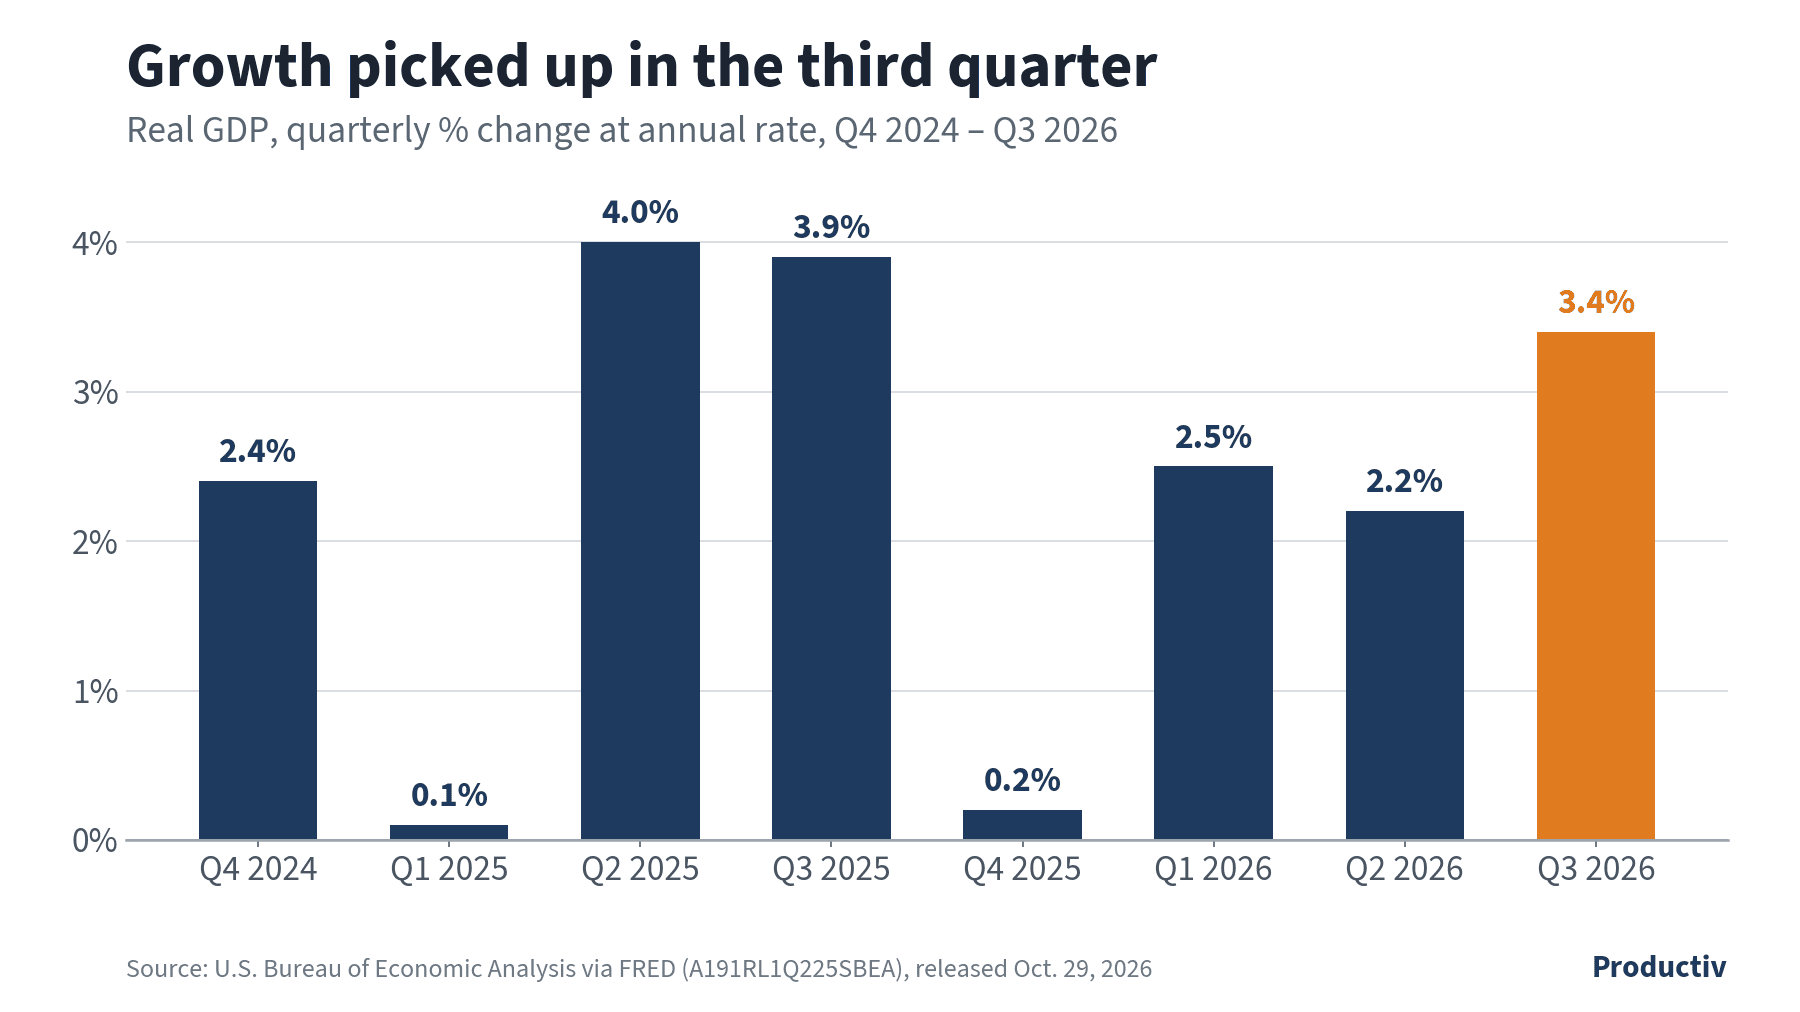
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/01-real-gdp.csv
Chart data (table)
| Quarter | Real GDP growth |
|---|---|
| Q4 2024 | 2.4% |
| Q1 2025 | 0.1% |
| Q2 2025 | 4.0% |
| Q3 2025 | 3.9% |
| Q4 2025 | 0.2% |
| Q1 2026 | 2.5% |
| Q2 2026 | 2.2% |
| Q3 2026 | 3.4% |
Q3 2026 is the BEA advance estimate (released Oct. 29, 2026); the second estimate is due Nov. 25, 2026.
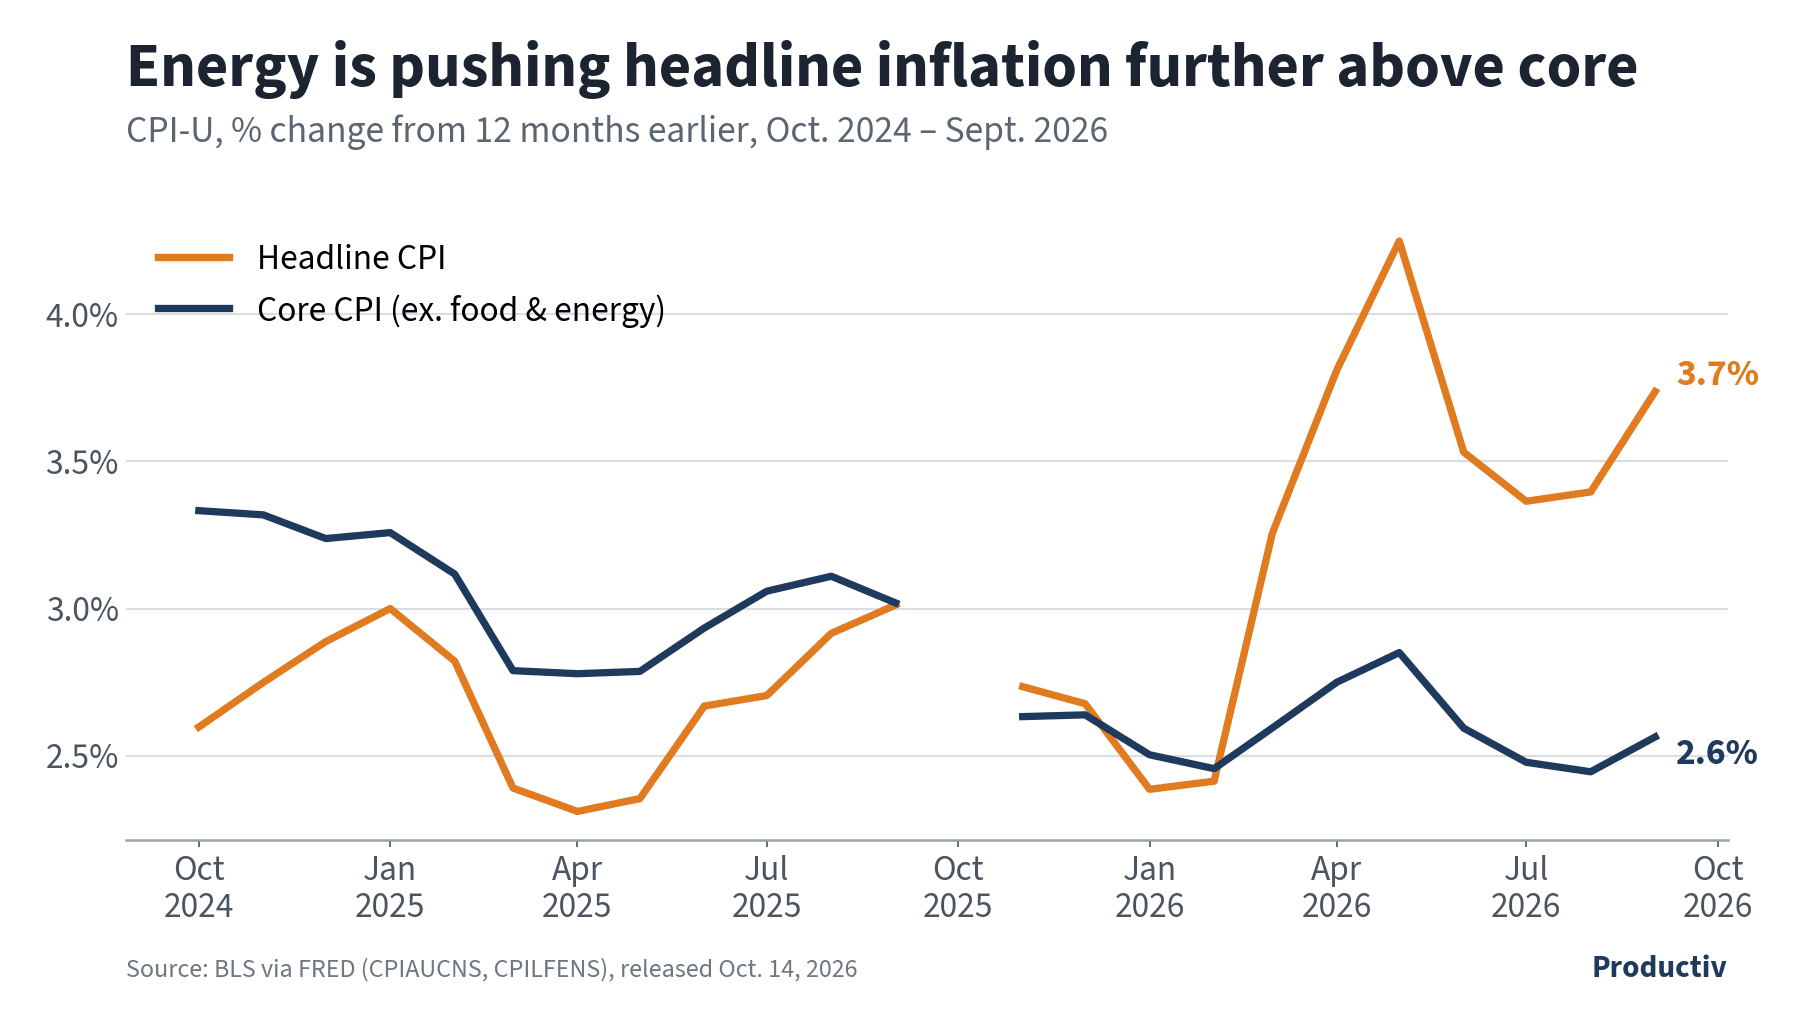
Download CSV Data- CPI, headline: +3.7% year over year in September 2026, up from 3.4% in August (BLS, released Oct. 14).
- CPI, core (excluding food and energy): +2.6% year over year. Energy was up 20.4% and gasoline up 34.2%. Transportation services were up 2.7%.
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/02-cpi.csv
Chart data (table)
| Month | Headline CPI | Core CPI (ex. food & energy) |
|---|---|---|
| Oct. 2024 | 2.6% | 3.3% |
| Nov. 2024 | 2.7% | 3.3% |
| Dec. 2024 | 2.9% | 3.2% |
| Jan. 2025 | 3.0% | 3.3% |
| Feb. 2025 | 2.8% | 3.1% |
| March 2025 | 2.4% | 2.8% |
| April 2025 | 2.3% | 2.8% |
| May 2025 | 2.4% | 2.8% |
| June 2025 | 2.7% | 2.9% |
| July 2025 | 2.7% | 3.1% |
| Aug. 2025 | 2.9% | 3.1% |
| Sept. 2025 | 3.0% | 3.0% |
| Oct. 2025 | n/a | n/a |
| Nov. 2025 | 2.7% | 2.6% |
| Dec. 2025 | 2.7% | 2.6% |
| Jan. 2026 | 2.4% | 2.5% |
| Feb. 2026 | 2.4% | 2.5% |
| March 2026 | 3.3% | 2.6% |
| April 2026 | 3.8% | 2.8% |
| May 2026 | 4.2% | 2.9% |
| June 2026 | 3.5% | 2.6% |
| July 2026 | 3.4% | 2.5% |
| Aug. 2026 | 3.4% | 2.4% |
| Sept. 2026 | 3.7% | 2.6% |
n/a: October 2025 CPI was not collected (federal shutdown).
Download CSV Data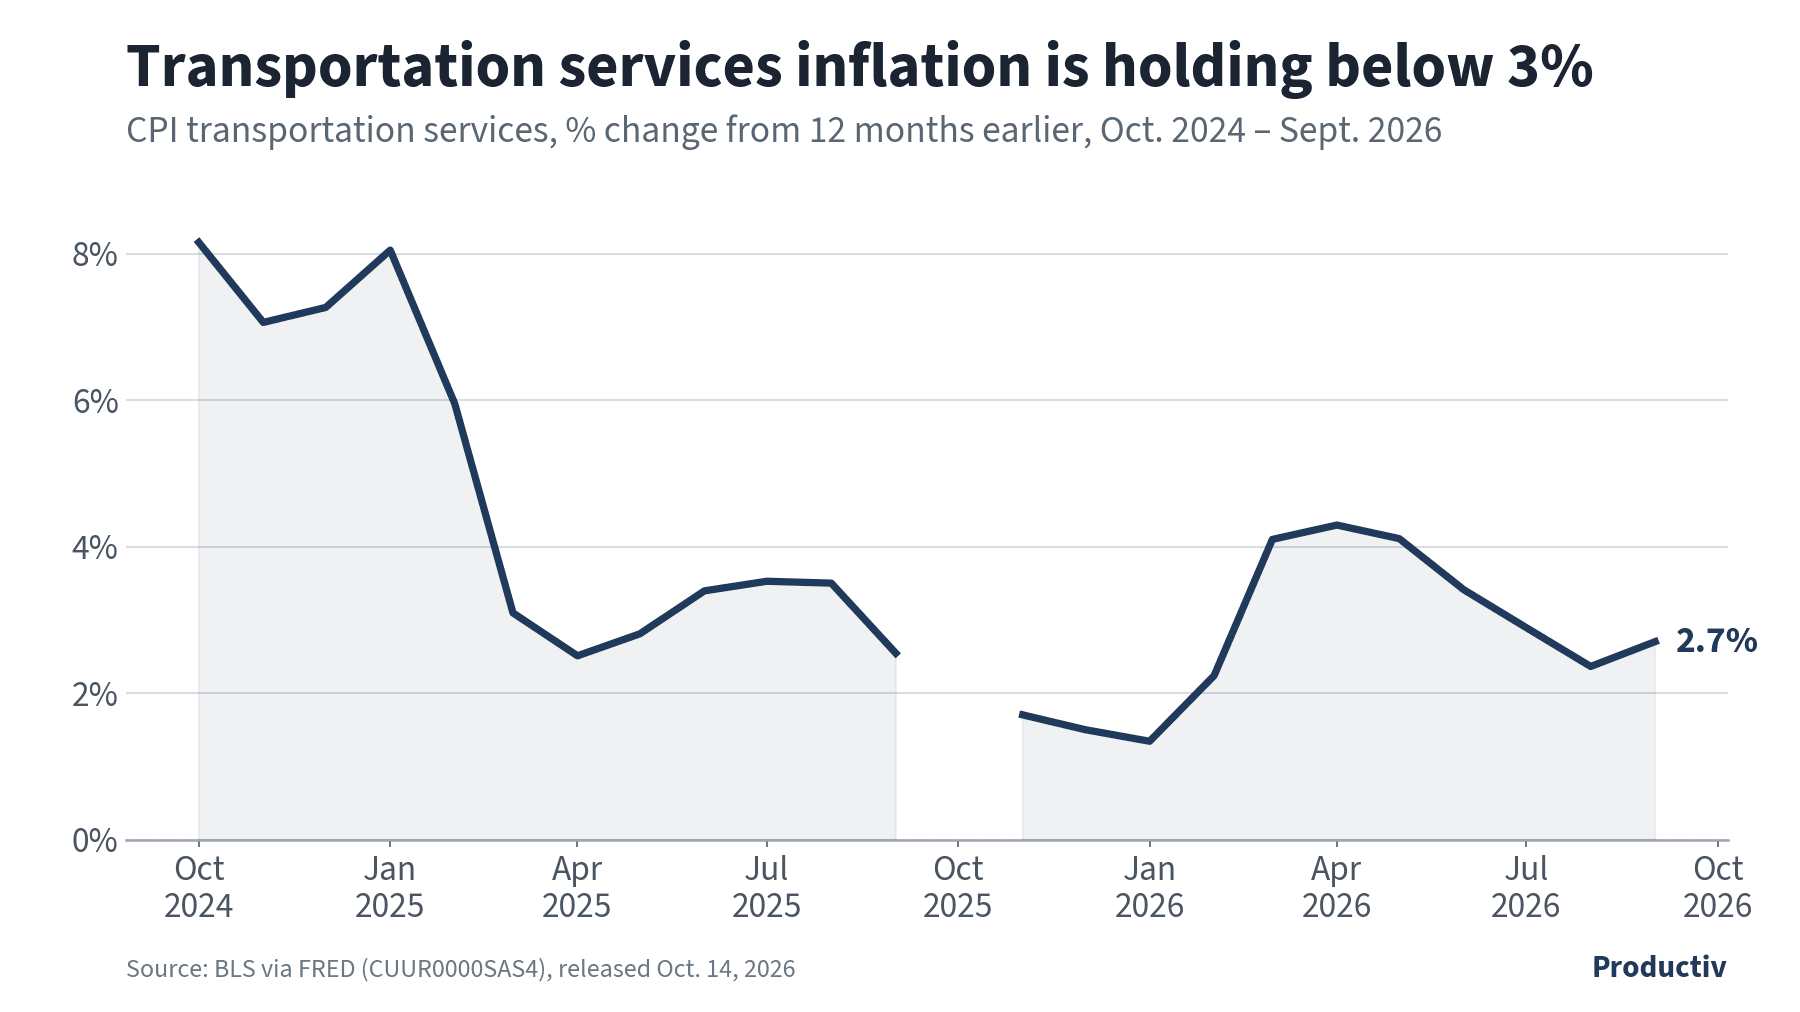
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/10-cpi-transport-services.csv
Chart data (table)
| Month | Transportation services CPI |
|---|---|
| Oct. 2024 | 8.2% |
| Nov. 2024 | 7.1% |
| Dec. 2024 | 7.3% |
| Jan. 2025 | 8.0% |
| Feb. 2025 | 6.0% |
| March 2025 | 3.1% |
| April 2025 | 2.5% |
| May 2025 | 2.8% |
| June 2025 | 3.4% |
| July 2025 | 3.5% |
| Aug. 2025 | 3.5% |
| Sept. 2025 | 2.5% |
| Oct. 2025 | n/a |
| Nov. 2025 | 1.7% |
| Dec. 2025 | 1.5% |
| Jan. 2026 | 1.3% |
| Feb. 2026 | 2.2% |
| March 2026 | 4.1% |
| April 2026 | 4.3% |
| May 2026 | 4.1% |
| June 2026 | 3.4% |
| July 2026 | 2.9% |
| Aug. 2026 | 2.4% |
| Sept. 2026 | 2.7% |
n/a: October 2025 CPI was not collected (federal shutdown).
Download CSV Data- Producer Price Index, final demand: +1.3% month over month (seasonally adjusted) and +6.3% year over year in September 2026 (BLS, released Oct. 15).
- PPI core (excluding foods, energy, and trade services): +0.5% month over month and +5.0% year over year.
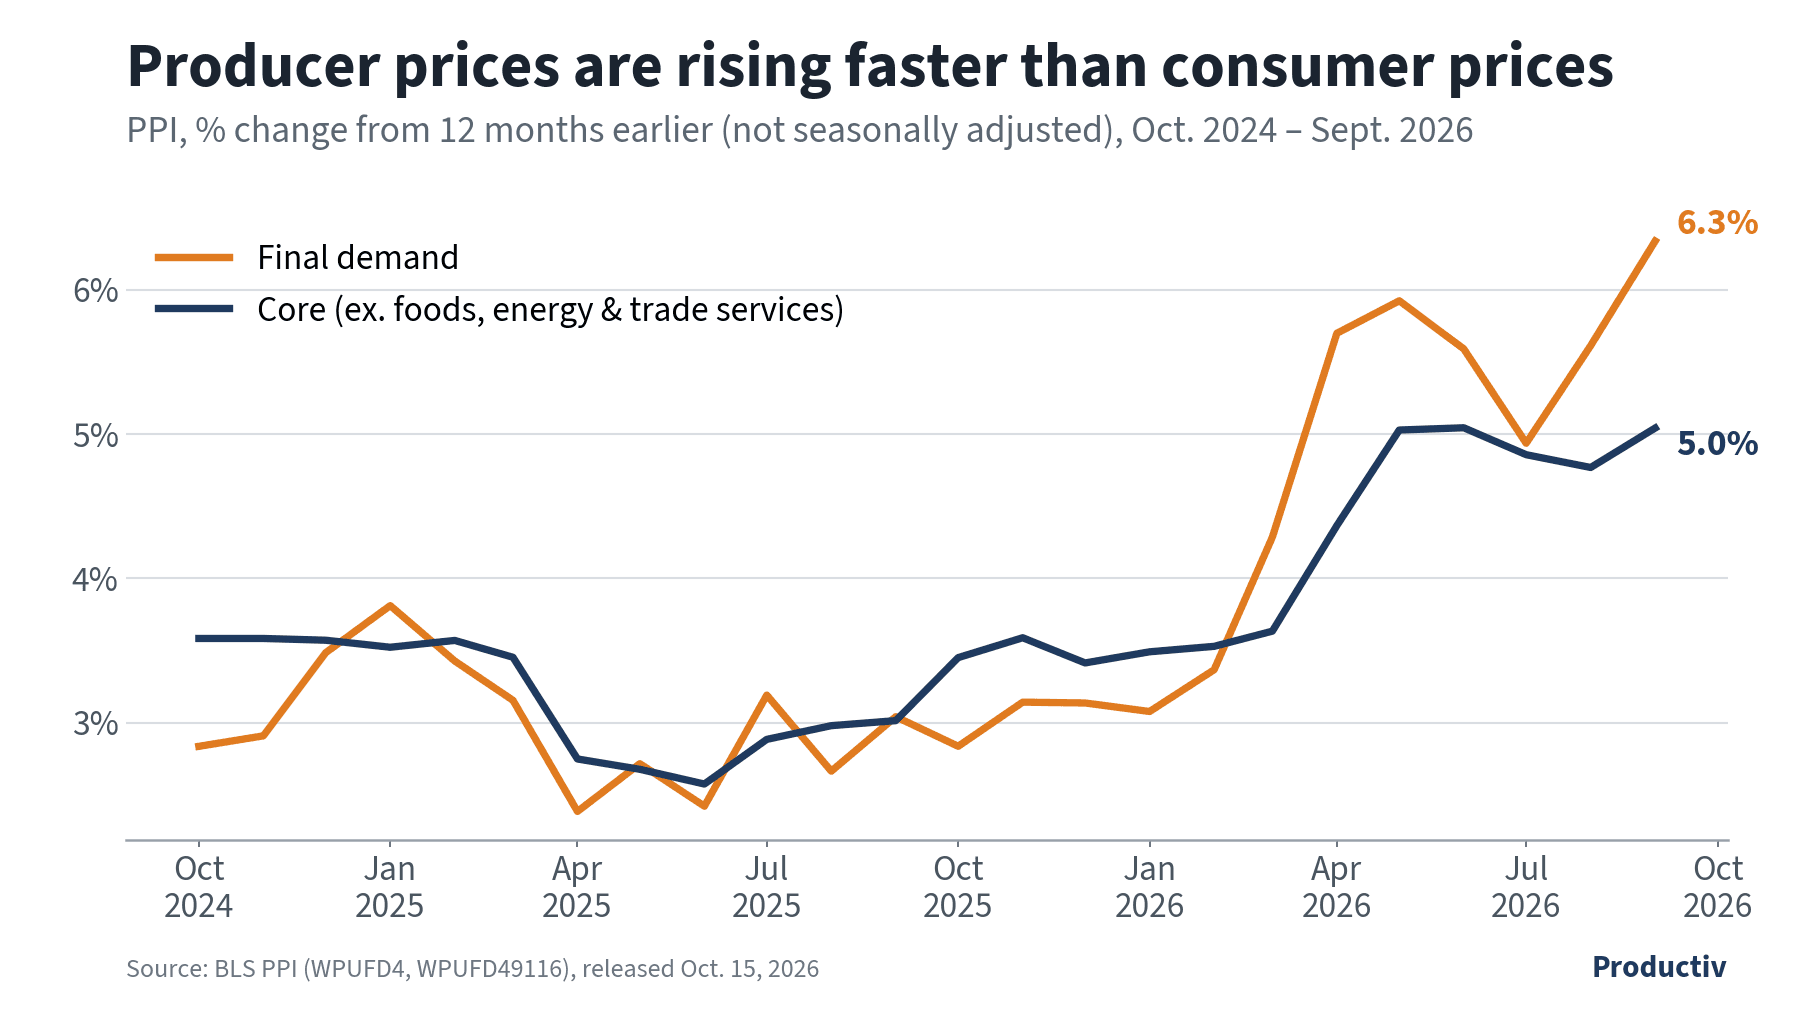
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/03-ppi.csv
Chart data (table)
| Month | Final demand | Core (ex. foods, energy & trade services) |
|---|---|---|
| Oct. 2024 | 2.8% | 3.6% |
| Nov. 2024 | 2.9% | 3.6% |
| Dec. 2024 | 3.5% | 3.6% |
| Jan. 2025 | 3.8% | 3.5% |
| Feb. 2025 | 3.4% | 3.6% |
| March 2025 | 3.2% | 3.5% |
| April 2025 | 2.4% | 2.7% |
| May 2025 | 2.7% | 2.7% |
| June 2025 | 2.4% | 2.6% |
| July 2025 | 3.2% | 2.9% |
| Aug. 2025 | 2.7% | 3.0% |
| Sept. 2025 | 3.0% | 3.0% |
| Oct. 2025 | 2.8% | 3.5% |
| Nov. 2025 | 3.1% | 3.6% |
| Dec. 2025 | 3.1% | 3.4% |
| Jan. 2026 | 3.1% | 3.5% |
| Feb. 2026 | 3.4% | 3.5% |
| March 2026 | 4.3% | 3.6% |
| April 2026 | 5.7% | 4.4% |
| May 2026 | 5.9% | 5.0% |
| June 2026 | 5.6% | 5.0% |
| July 2026 | 4.9% | 4.9% |
| Aug. 2026 | 5.6% | 4.8% |
| Sept. 2026 | 6.3% | 5.0% |
Recent months are preliminary.
Download CSV Data- ISM Manufacturing PMI: 55.5 in October 2026, up 1.0 from 54.5 in September (ISM, released Nov. 2). That's the 10th straight month of expansion (above 50 = growth).
- New orders: 55.5 (+0.2)
- Employment: 52.4 (−0.3)
- Prices: 75.2 (−2.7), still high
- Industrial production, manufacturing (NAICS, FRED IPMAN): +1.4% year over year in September 2026, with output up 0.3% on the month (Federal Reserve G.17, released Oct. 16).
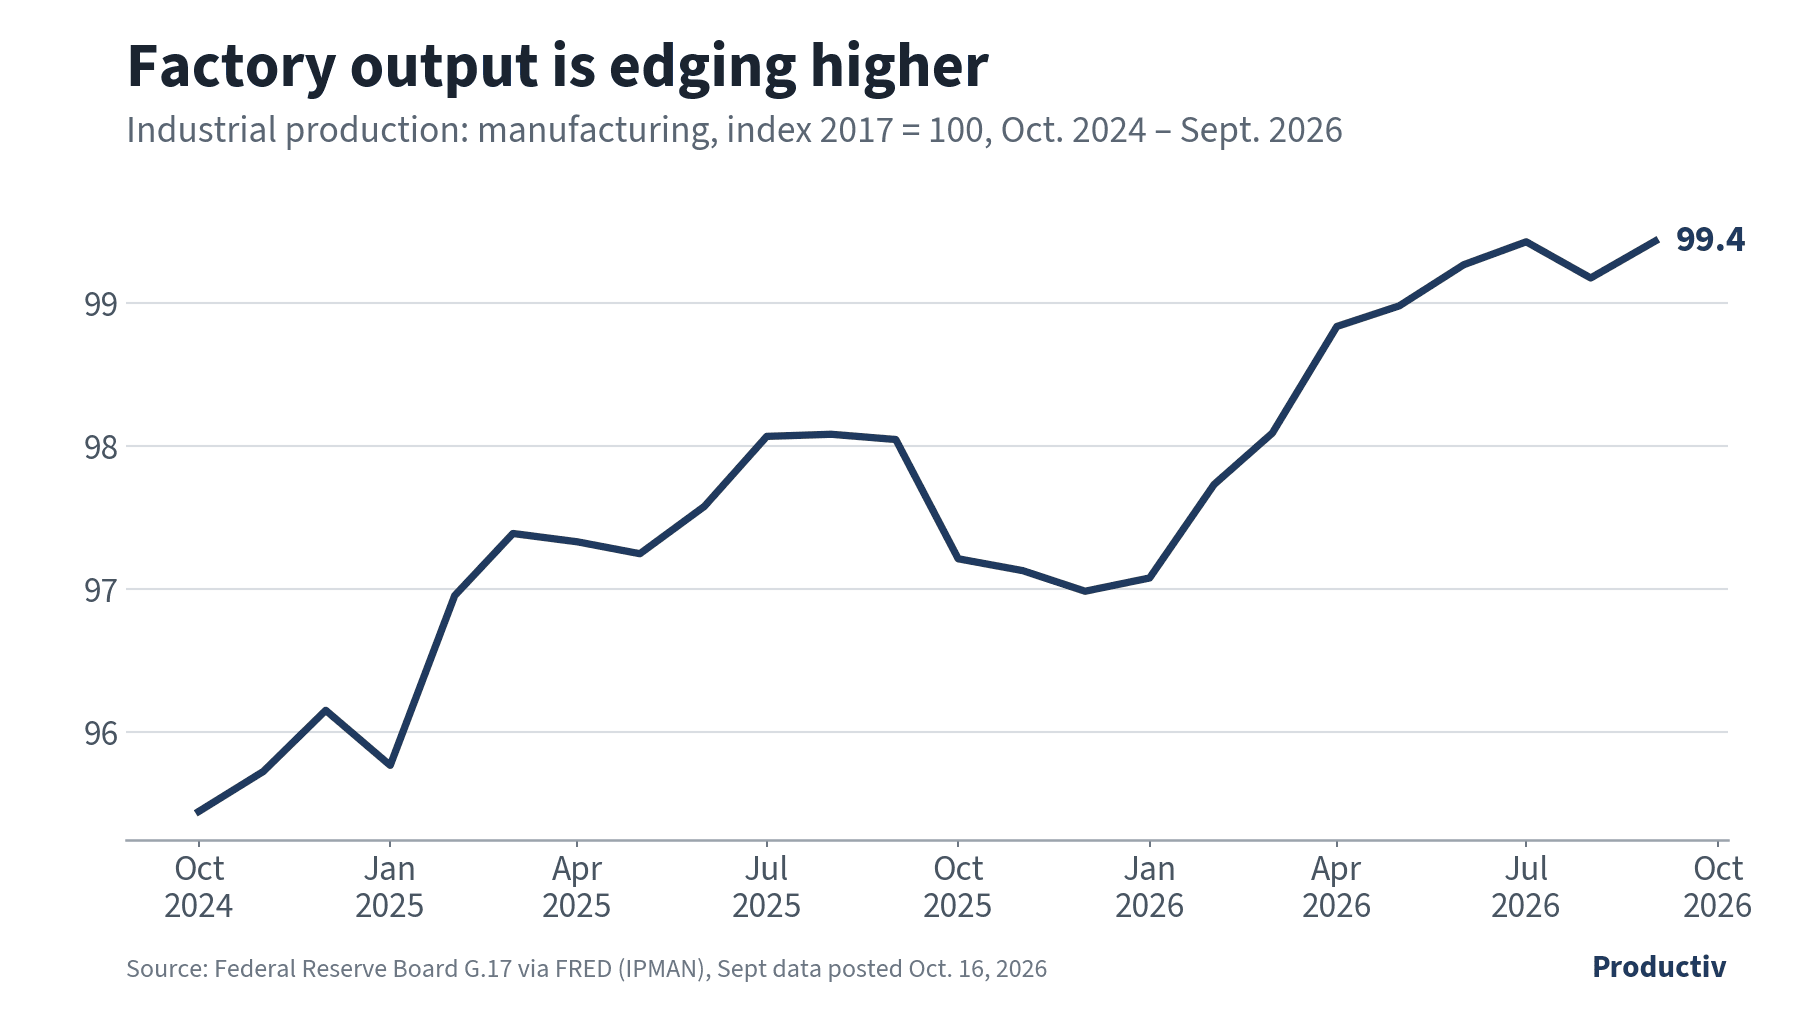
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/12-ip-manufacturing.csv
Chart data (table)
| Month | Index | % change from a year earlier |
|---|---|---|
| Oct. 2024 | 95.4 | -1.4% |
| Nov. 2024 | 95.7 | -1.6% |
| Dec. 2024 | 96.2 | -1.1% |
| Jan. 2025 | 95.8 | +0.0% |
| Feb. 2025 | 97.0 | +0.0% |
| March 2025 | 97.4 | +0.3% |
| April 2025 | 97.3 | +0.8% |
| May 2025 | 97.2 | +0.1% |
| June 2025 | 97.6 | +0.7% |
| July 2025 | 98.1 | +2.0% |
| Aug. 2025 | 98.1 | +1.5% |
| Sept. 2025 | 98.0 | +2.0% |
| Oct. 2025 | 97.2 | +1.9% |
| Nov. 2025 | 97.1 | +1.5% |
| Dec. 2025 | 97.0 | +0.9% |
| Jan. 2026 | 97.1 | +1.4% |
| Feb. 2026 | 97.7 | +0.8% |
| March 2026 | 98.1 | +0.7% |
| April 2026 | 98.8 | +1.5% |
| May 2026 | 99.0 | +1.8% |
| June 2026 | 99.3 | +1.7% |
| July 2026 | 99.4 | +1.4% |
| Aug. 2026 | 99.2 | +1.1% |
| Sept. 2026 | 99.4 | +1.4% |
- E-commerce share of retail: 17.1% in Q2 2026 (Census Bureau). The Q3 figure is due Nov. 19.
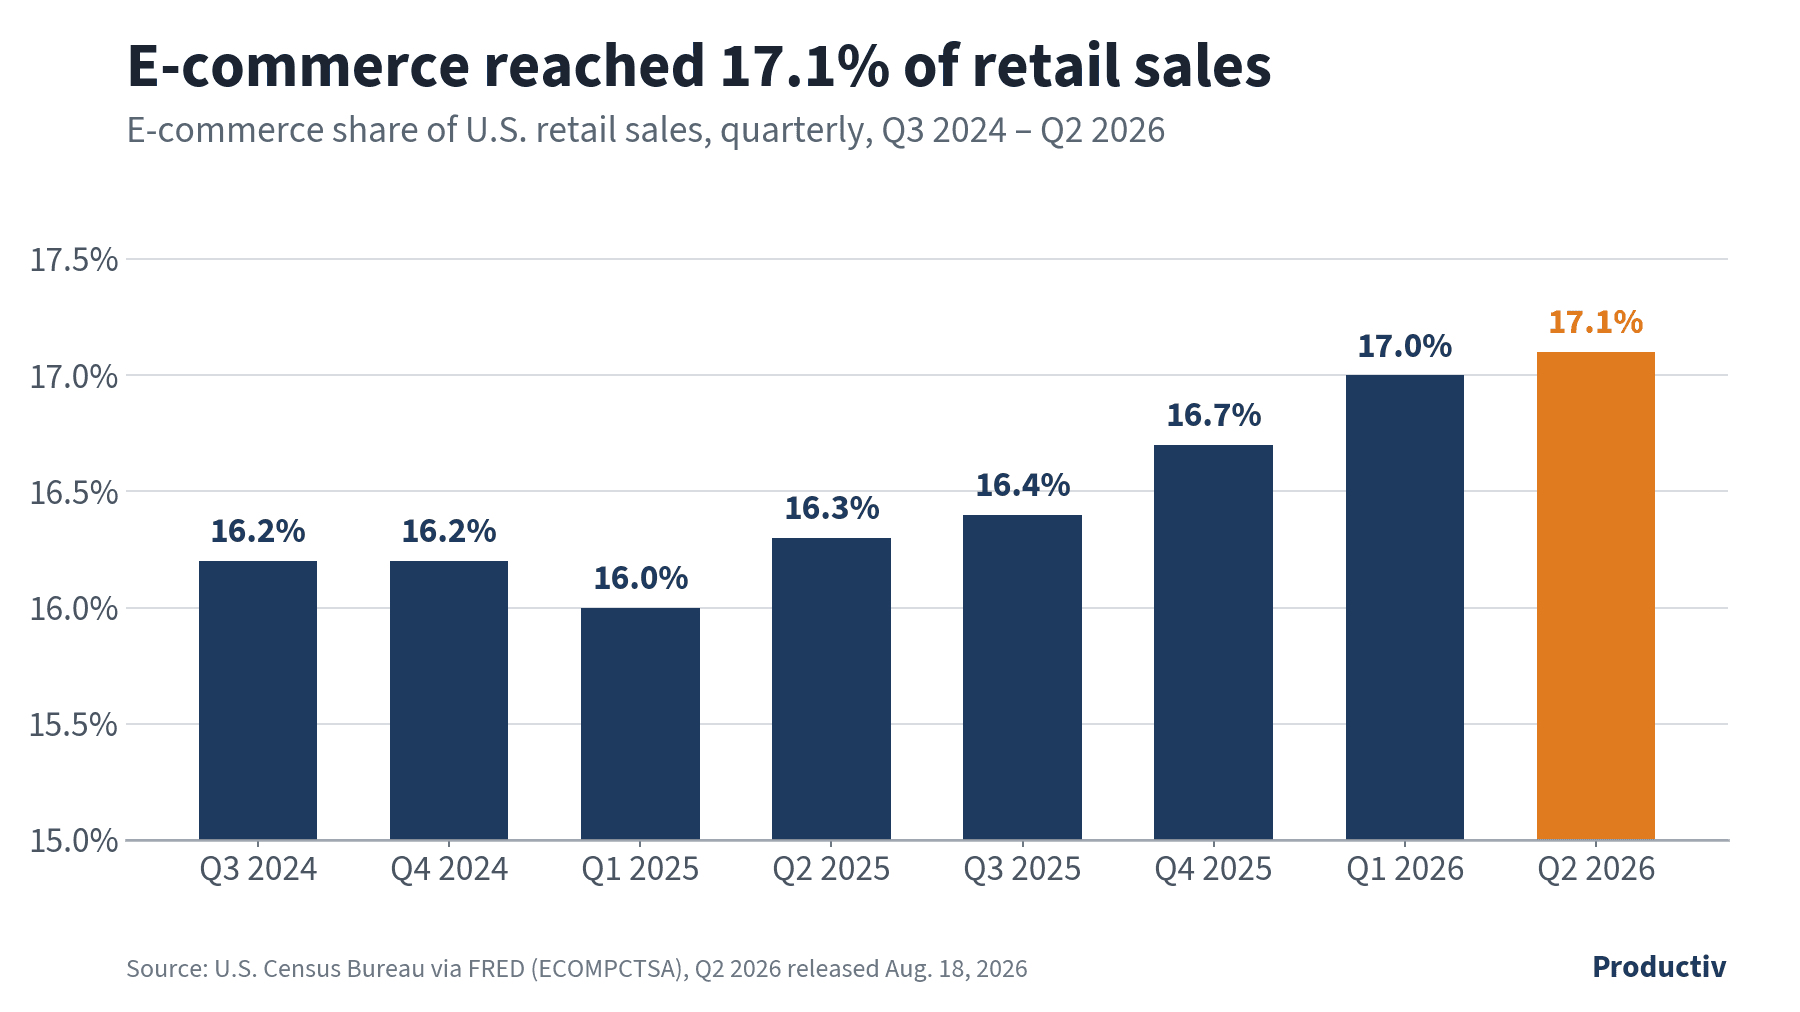
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/11-ecommerce-share.csv
Chart data (table)
| Quarter | E-commerce share |
|---|---|
| Q3 2024 | 16.2% |
| Q4 2024 | 16.2% |
| Q1 2025 | 16.0% |
| Q2 2025 | 16.3% |
| Q3 2025 | 16.4% |
| Q4 2025 | 16.7% |
| Q1 2026 | 17.0% |
| Q2 2026 | 17.1% |
What it means
- Shippers & manufacturers
- Producer prices are up 6.3% year over year (September), faster than the 3.7% rise in consumer prices. Packaging and component costs are still climbing, so set 2027 cost assumptions on that gap, not on CPI.
- 3PLs & warehouse operators
- Core PPI is up 5.0%. Supply bills keep rising, so check the pass-through terms in your contracts before peak volume arrives.
- Transportation & fleets
- GDP grew 3.4% in Q3 and ISM new orders are at 55.5 (October), so industrial freight demand is still growing.
Sources: BEA GDP, Q3 2026 advance estimate, BLS CPI September 2026, BLS PPI September 2026, ISM Manufacturing PMI, October 2026, Federal Reserve G.17, FRED IPMAN, Census quarterly e-commerce
2. Credit & Rates
- Fed funds target range: held at 3.75%–4.00% at the Oct. 27–28 FOMC meeting (statement released Oct. 28). Two members dissented in favor of a 0.25-point increase. The next meeting is Dec. 8–9.
- Effective fed funds rate: 3.88% on Nov. 2.
- 10-year Treasury: 4.91% on Nov. 2, down from 5.24% on Oct. 1 and up from 4.13% a year ago.
- 30-year fixed mortgage (Freddie Mac PMMS): 7.24% for the week of Oct. 29, up from 6.17% a year ago.
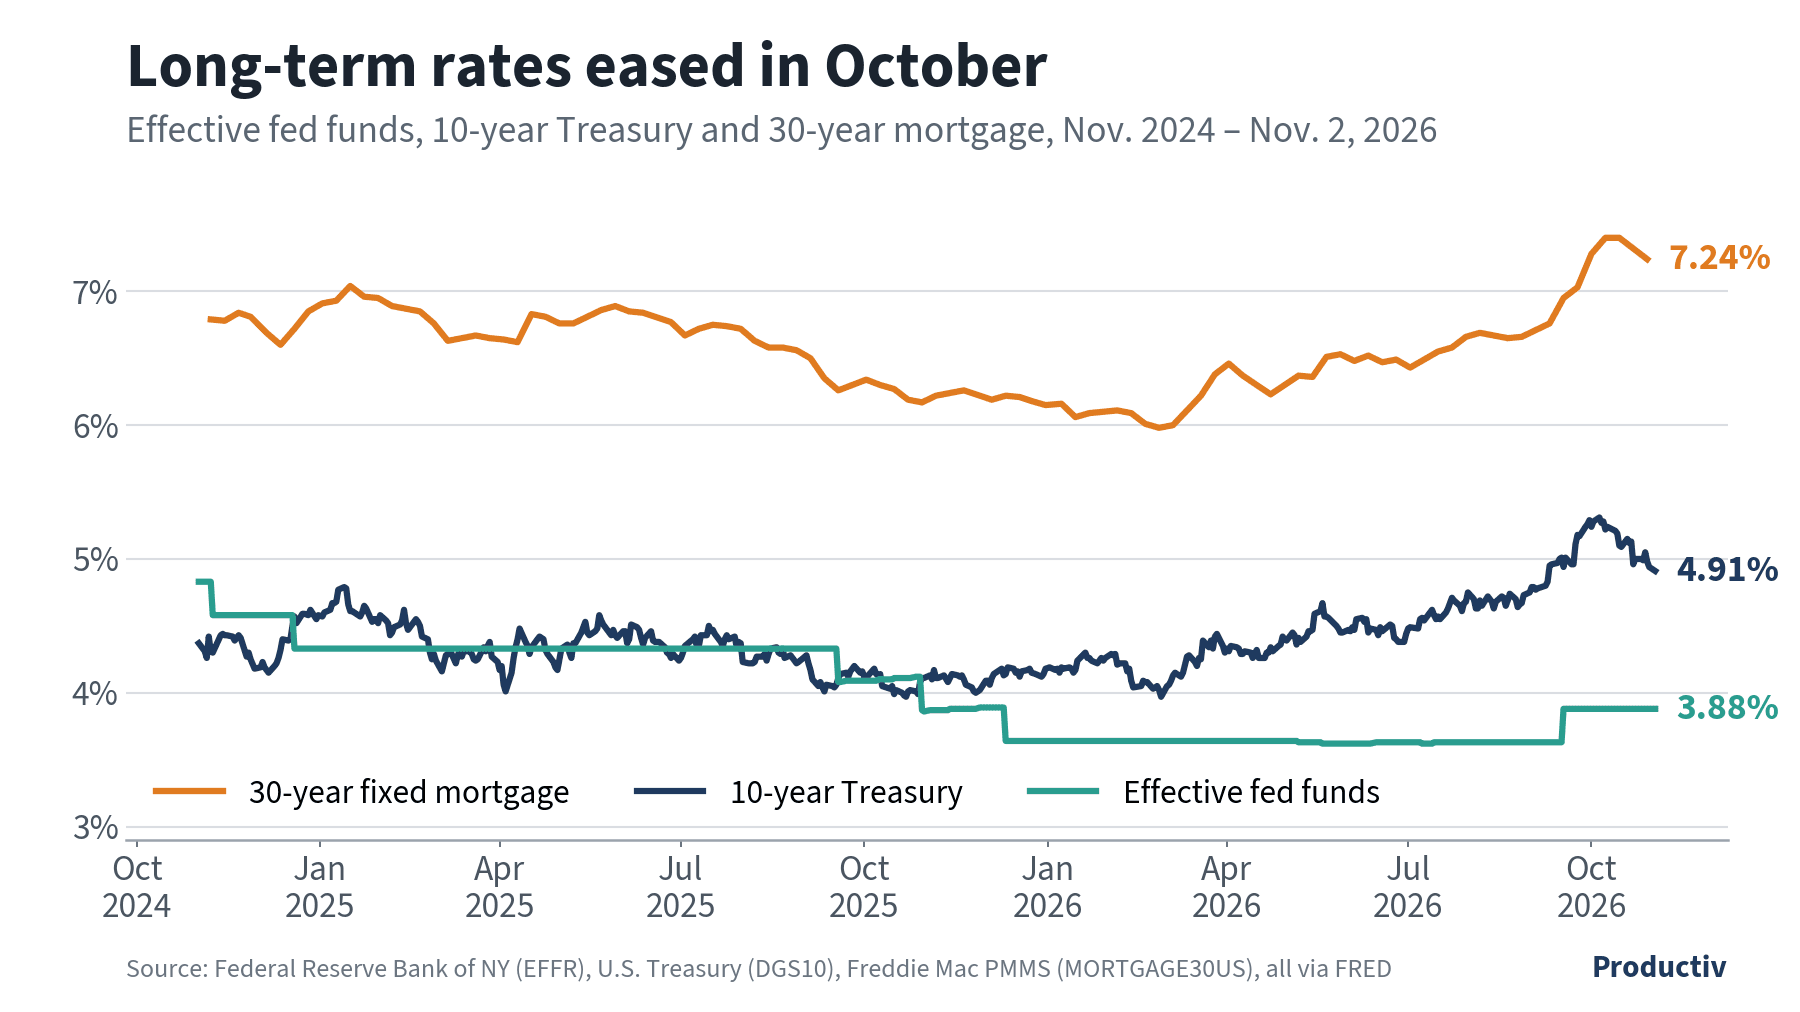
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/15-rates.csv
Chart data (table)
| Month | Effective fed funds | 10-year Treasury | 30-year fixed mortgage |
|---|---|---|---|
| Nov. 2024 | 4.58% | 4.18% | 6.81% |
| Dec. 2024 | 4.33% | 4.58% | 6.85% |
| Jan. 2025 | 4.33% | 4.58% | 6.95% |
| Feb. 2025 | 4.33% | 4.24% | 6.76% |
| March 2025 | 4.33% | 4.23% | 6.65% |
| April 2025 | 4.33% | 4.17% | 6.81% |
| May 2025 | 4.33% | 4.41% | 6.89% |
| June 2025 | 4.33% | 4.24% | 6.77% |
| July 2025 | 4.33% | 4.37% | 6.72% |
| Aug. 2025 | 4.33% | 4.23% | 6.56% |
| Sept. 2025 | 4.09% | 4.16% | 6.30% |
| Oct. 2025 | 3.86% | 4.11% | 6.17% |
| Nov. 2025 | 3.89% | 4.02% | 6.23% |
| Dec. 2025 | 3.64% | 4.18% | 6.15% |
| Jan. 2026 | 3.64% | 4.26% | 6.10% |
| Feb. 2026 | 3.64% | 3.97% | 5.98% |
| March 2026 | 3.64% | 4.30% | 6.38% |
| April 2026 | 3.64% | 4.40% | 6.30% |
| May 2026 | 3.62% | 4.45% | 6.53% |
| June 2026 | 3.63% | 4.44% | 6.49% |
| July 2026 | 3.63% | 4.75% | 6.66% |
| Aug. 2026 | 3.63% | 4.75% | 6.66% |
| Sept. 2026 | 3.88% | 5.29% | 7.03% |
| Oct. 2026 | 3.88% | 4.94% | 7.24% |
| Nov. 2026 (Nov. 2) | 3.88% | 4.91% | n/a |
Each cell is the last published value in that month; the download has every daily and weekly reading.
Download CSV Data- Bank prime loan rate: 7.00%, unchanged since the September hike (7.25% a year ago).
What it means
- Shippers & manufacturers
- The 10-year Treasury eased to 4.91% (Nov. 2) from 5.24% on Oct. 1, but it is still well above last year's 4.13%. Carrying extra peak inventory is a bit cheaper than a month ago, not cheap.
- 3PLs & warehouse operators
- With prime at 7.00%, automation and equipment projects still need a short payback. Higher rates also keep new warehouse construction slow, which supports rents.
- Transportation & fleets
- Financing costs are flat this month at a 7.00% prime rate. Price extending current equipment against replacement before 2027 orders.
Sources: Federal Reserve FOMC statement, Oct. 28, 2026, FOMC calendar, FRED: EFFR, MORTGAGE30US, DGS10, DPRIME
3. Labor
The October jobs report comes out Nov. 6, so the payroll figures below are still September's (released Oct. 2).
- Transportation & warehousing employment: 6,608,700 in September (preliminary), +7,600 from August.
- Warehousing & storage: 1,831,800, down 4,100 from August and 21,600 from a year ago.
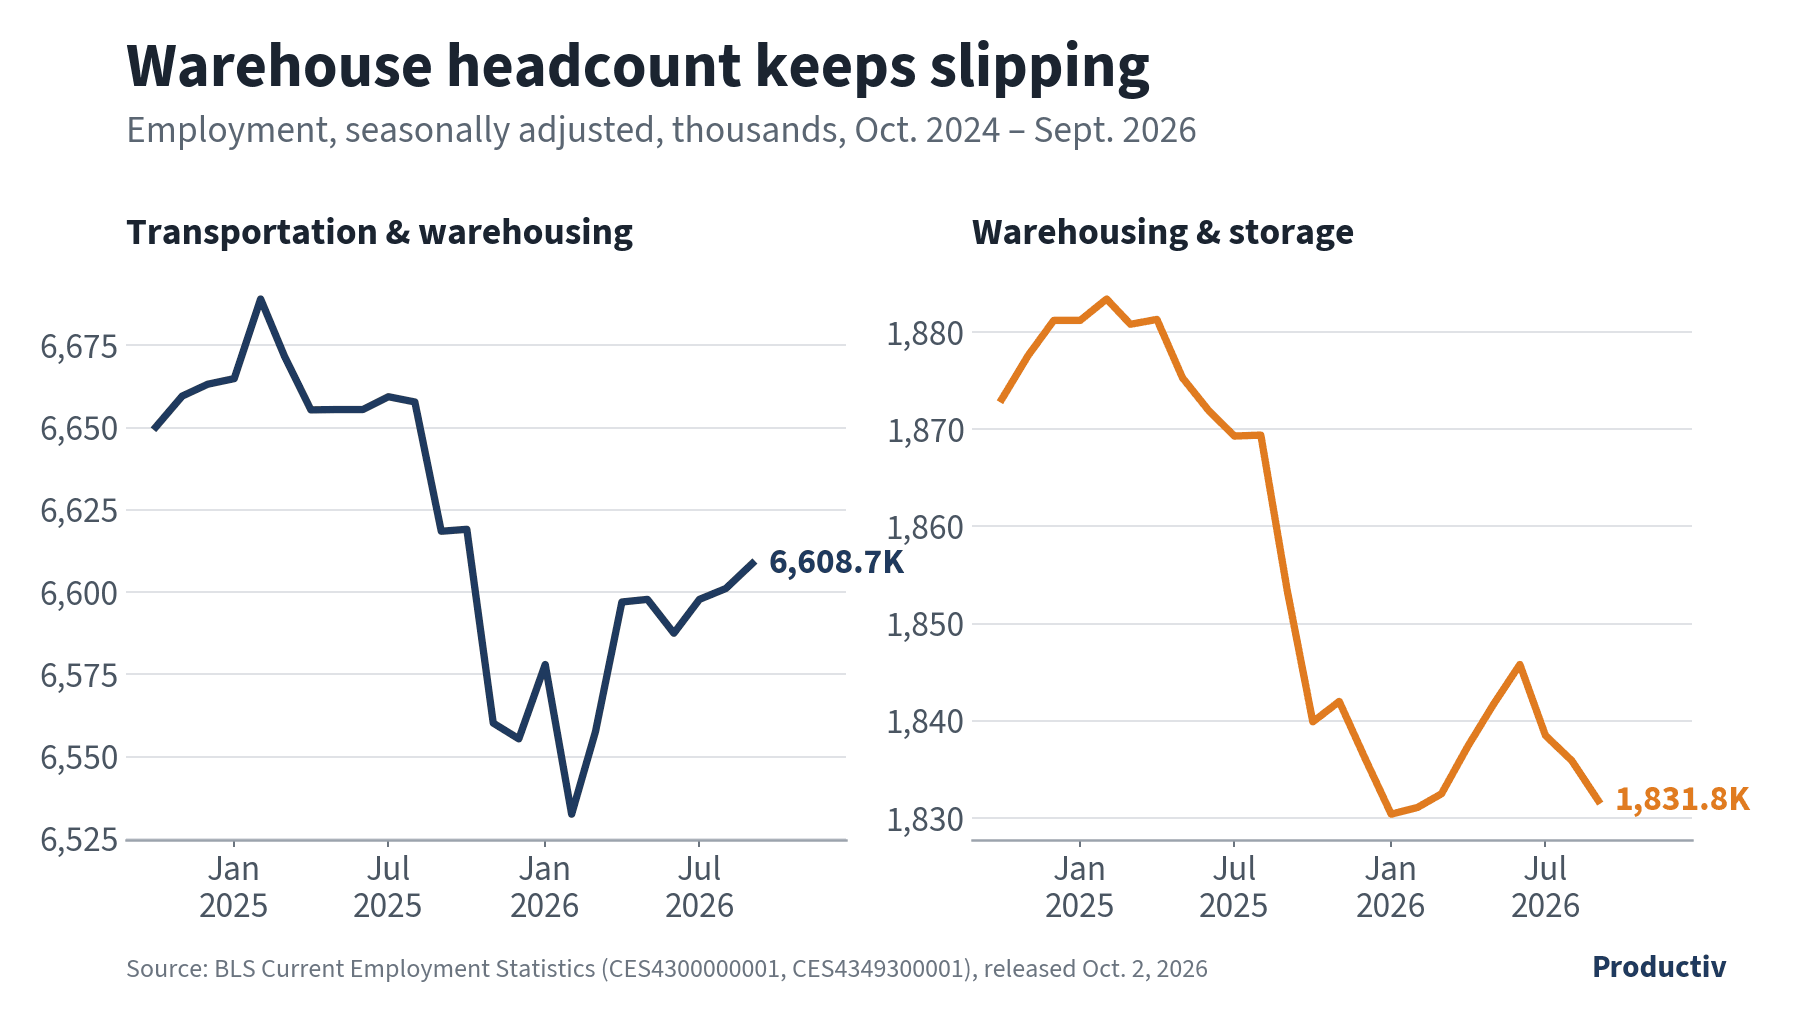
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/04-tw-employment.csv
Chart data (table)
| Month | Transportation & warehousing | Warehousing & storage |
|---|---|---|
| Oct. 2024 | 6,650.2 | 1,873.1 |
| Nov. 2024 | 6,659.6 | 1,877.6 |
| Dec. 2024 | 6,663.2 | 1,881.2 |
| Jan. 2025 | 6,664.9 | 1,881.2 |
| Feb. 2025 | 6,689.1 | 1,883.4 |
| March 2025 | 6,671.7 | 1,880.8 |
| April 2025 | 6,655.4 | 1,881.3 |
| May 2025 | 6,655.5 | 1,875.3 |
| June 2025 | 6,655.5 | 1,871.9 |
| July 2025 | 6,659.4 | 1,869.3 |
| Aug. 2025 | 6,657.8 | 1,869.4 |
| Sept. 2025 | 6,618.5 | 1,853.4 |
| Oct. 2025 | 6,619.1 | 1,839.9 |
| Nov. 2025 | 6,560.2 | 1,842.0 |
| Dec. 2025 | 6,555.4 | 1,836.2 |
| Jan. 2026 | 6,578.0 | 1,830.4 |
| Feb. 2026 | 6,532.5 | 1,831.1 |
| March 2026 | 6,557.6 | 1,832.5 |
| April 2026 | 6,597.0 | 1,837.4 |
| May 2026 | 6,597.8 | 1,841.7 |
| June 2026 | 6,587.5 | 1,845.8 |
| July 2026 | 6,597.8 | 1,838.5 |
| Aug. 2026 | 6,601.1 | 1,835.9 |
| Sept. 2026 | 6,608.7 | 1,831.8 |
Aug.–Sept. 2026 are preliminary. October data are due Nov. 6, 2026.
Download CSV Data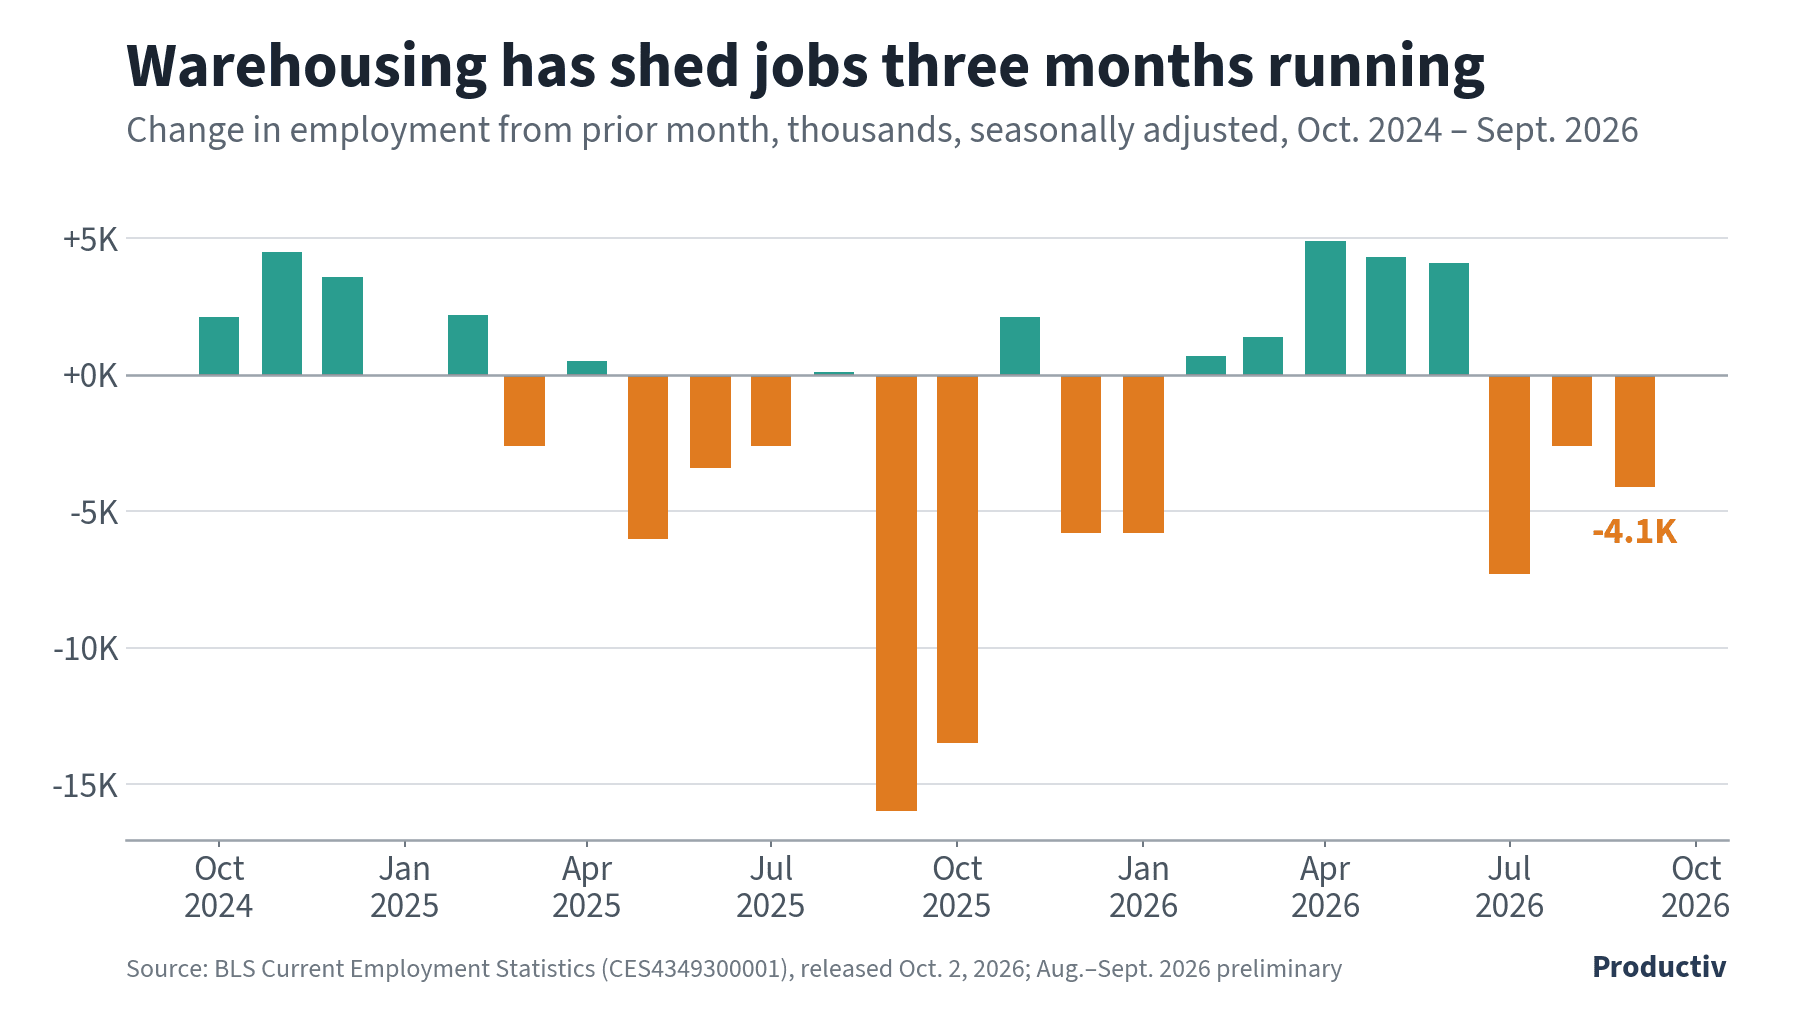
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/08-warehousing-mom.csv
Chart data (table)
| Month | Change (thousands) |
|---|---|
| Oct. 2024 | +2.1 |
| Nov. 2024 | +4.5 |
| Dec. 2024 | +3.6 |
| Jan. 2025 | +0.0 |
| Feb. 2025 | +2.2 |
| March 2025 | -2.6 |
| April 2025 | +0.5 |
| May 2025 | -6.0 |
| June 2025 | -3.4 |
| July 2025 | -2.6 |
| Aug. 2025 | +0.1 |
| Sept. 2025 | -16.0 |
| Oct. 2025 | -13.5 |
| Nov. 2025 | +2.1 |
| Dec. 2025 | -5.8 |
| Jan. 2026 | -5.8 |
| Feb. 2026 | +0.7 |
| March 2026 | +1.4 |
| April 2026 | +4.9 |
| May 2026 | +4.3 |
| June 2026 | +4.1 |
| July 2026 | -7.3 |
| Aug. 2026 | -2.6 |
| Sept. 2026 | -4.1 |
Aug.–Sept. 2026 are preliminary. October data are due Nov. 6, 2026.
Download CSV Data- Average hourly earnings, transportation & warehousing: $32.78, up 3.1% year over year. September CPI inflation was 3.7%, so real pay fell.
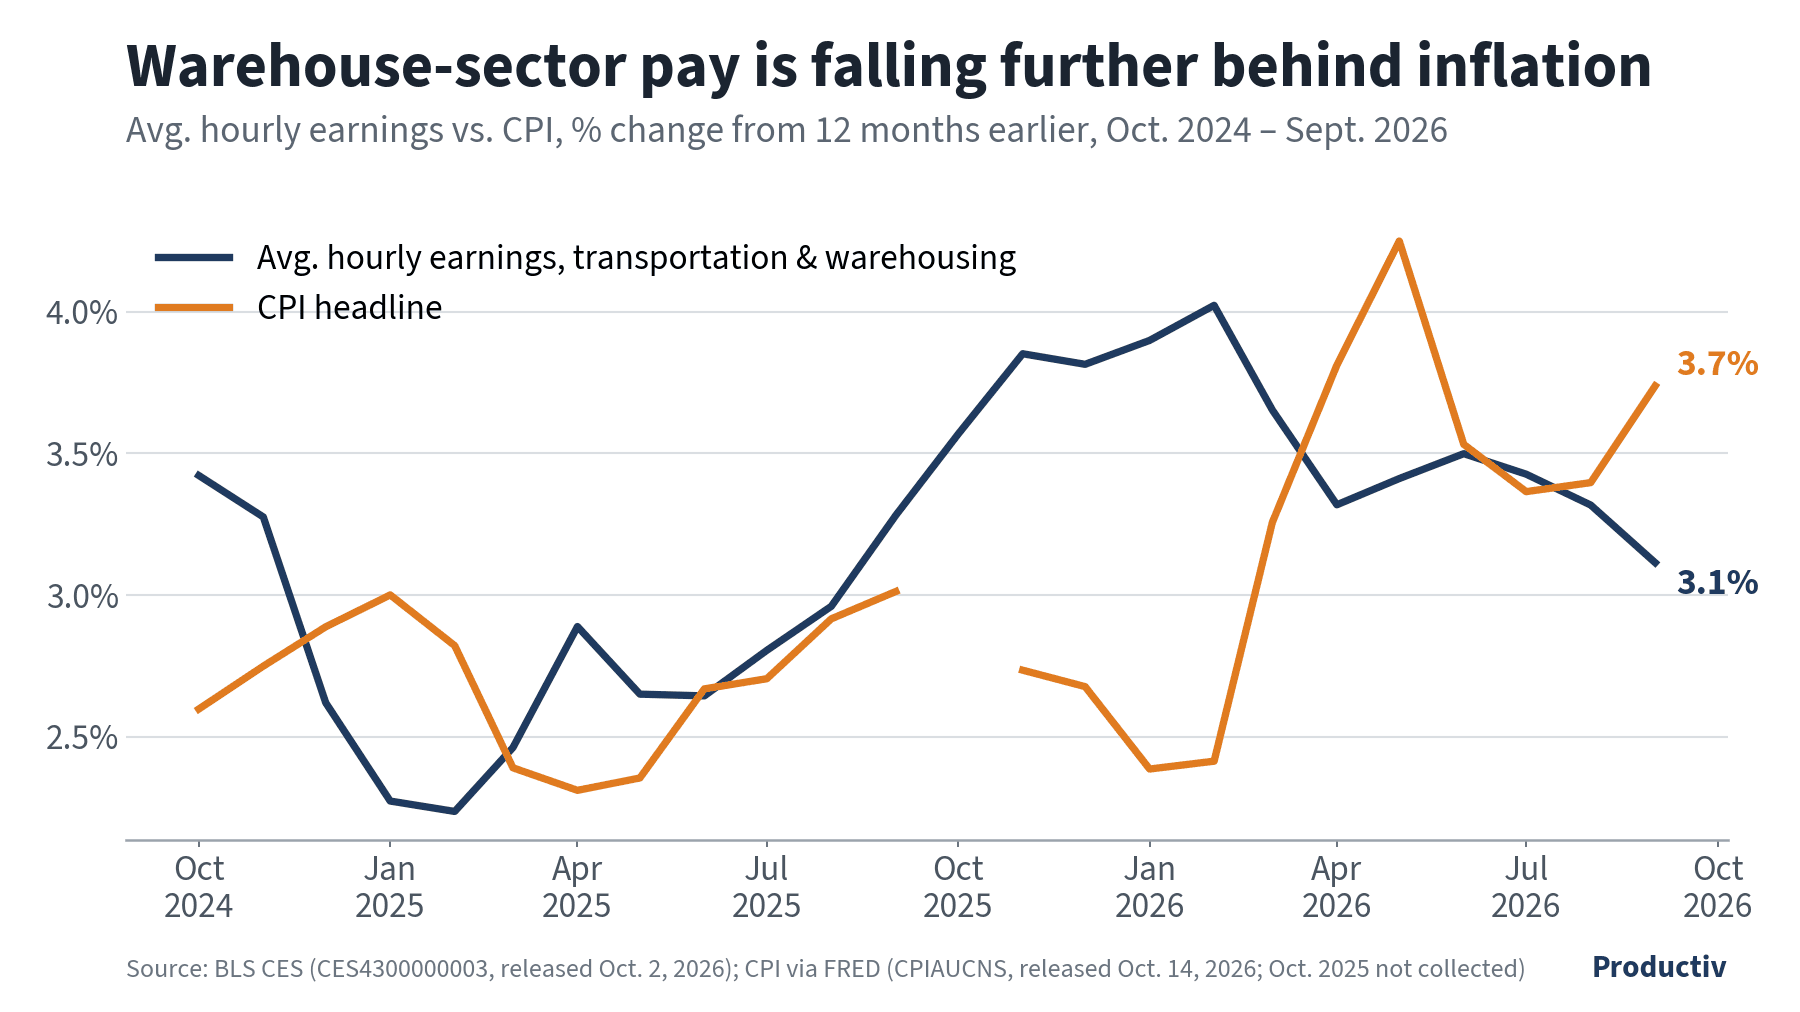
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/05-pay-vs-cpi.csv
Chart data (table)
| Month | Avg. hourly earnings | CPI headline |
|---|---|---|
| Oct. 2024 | 3.4% | 2.6% |
| Nov. 2024 | 3.3% | 2.7% |
| Dec. 2024 | 2.6% | 2.9% |
| Jan. 2025 | 2.3% | 3.0% |
| Feb. 2025 | 2.2% | 2.8% |
| March 2025 | 2.5% | 2.4% |
| April 2025 | 2.9% | 2.3% |
| May 2025 | 2.7% | 2.4% |
| June 2025 | 2.6% | 2.7% |
| July 2025 | 2.8% | 2.7% |
| Aug. 2025 | 3.0% | 2.9% |
| Sept. 2025 | 3.3% | 3.0% |
| Oct. 2025 | 3.6% | n/a |
| Nov. 2025 | 3.9% | 2.7% |
| Dec. 2025 | 3.8% | 2.7% |
| Jan. 2026 | 3.9% | 2.4% |
| Feb. 2026 | 4.0% | 2.4% |
| March 2026 | 3.7% | 3.3% |
| April 2026 | 3.3% | 3.8% |
| May 2026 | 3.4% | 4.2% |
| June 2026 | 3.5% | 3.5% |
| July 2026 | 3.4% | 3.4% |
| Aug. 2026 | 3.3% | 3.4% |
| Sept. 2026 | 3.1% | 3.7% |
n/a: October 2025 CPI was not collected (federal shutdown).
Download CSV Data- Job openings and quits (JOLTS, transportation, warehousing & utilities, not seasonally adjusted): 364,000 openings in September. The quits rate was 2.1%, compared with 2.2% a year earlier (BLS, released Nov. 3). BLS revised August's quits rate from 2.0% to 2.3%.
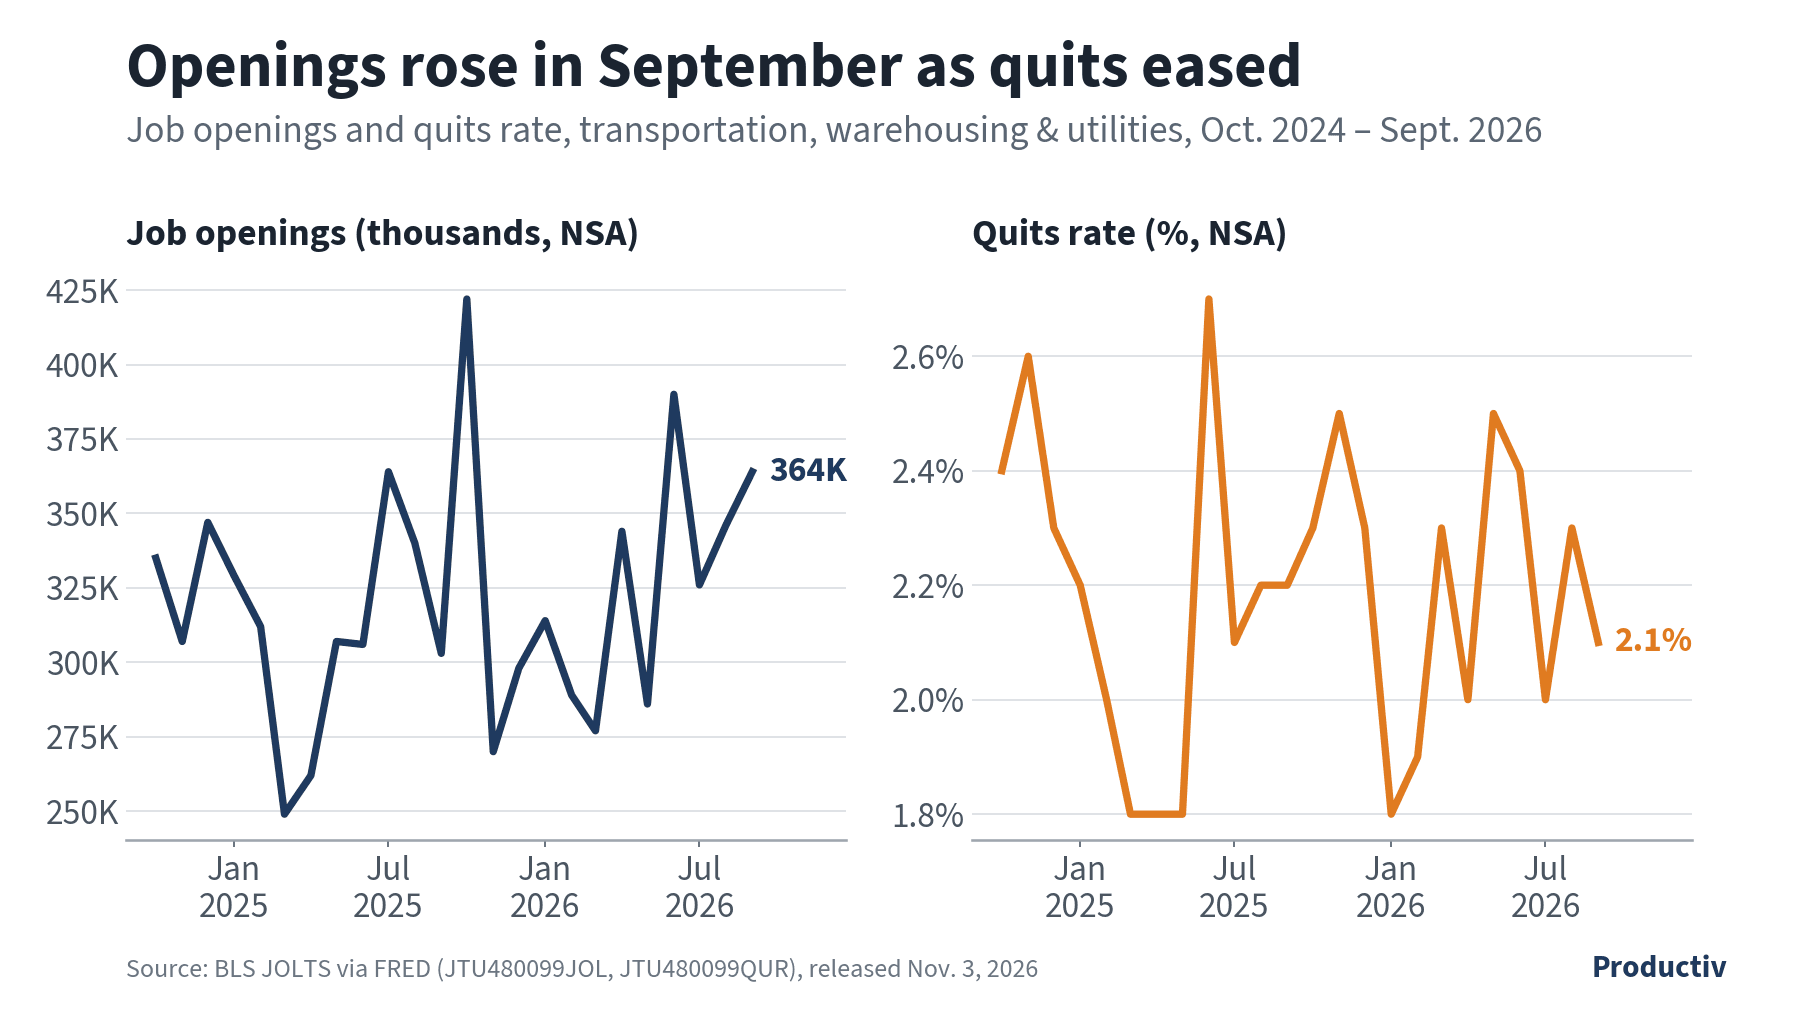
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/09-jolts-twu.csv
Chart data (table)
| Month | Job openings (thousands) | Quits rate |
|---|---|---|
| Oct. 2024 | 335 | 2.4% |
| Nov. 2024 | 307 | 2.6% |
| Dec. 2024 | 347 | 2.3% |
| Jan. 2025 | 329 | 2.2% |
| Feb. 2025 | 312 | 2.0% |
| March 2025 | 249 | 1.8% |
| April 2025 | 262 | 1.8% |
| May 2025 | 307 | 1.8% |
| June 2025 | 306 | 2.7% |
| July 2025 | 364 | 2.1% |
| Aug. 2025 | 340 | 2.2% |
| Sept. 2025 | 303 | 2.2% |
| Oct. 2025 | 422 | 2.3% |
| Nov. 2025 | 270 | 2.5% |
| Dec. 2025 | 298 | 2.3% |
| Jan. 2026 | 314 | 1.8% |
| Feb. 2026 | 289 | 1.9% |
| March 2026 | 277 | 2.3% |
| April 2026 | 344 | 2.0% |
| May 2026 | 286 | 2.5% |
| June 2026 | 390 | 2.4% |
| July 2026 | 326 | 2.0% |
| Aug. 2026 | 346 | 2.3% |
| Sept. 2026 | 364 | 2.1% |
September 2026 is preliminary. BLS revised August: openings from 353 to 346 thousand and the quits rate from 2.0% to 2.3%.
Download CSV DataWhat it means
- Shippers & manufacturers
- Warehousing and storage has 21,600 fewer jobs than a year ago (September, BLS), and quits eased to 2.1%. Staffing peak is not the main risk this year. Ask your 3PL where it will put your inventory instead.
- 3PLs & warehouse operators
- Pay is up 3.1% against 3.7% inflation (September), so real wages are falling. People are staying for now, but the trained operators who leave during peak are the expensive ones. Run the turnover cost before you set peak pay.
Sources: BLS Transportation & Warehousing, BLS Warehousing & Storage, BLS release schedule, BLS JOLTS, September 2026
4. Industrial Real Estate (Q3 2026)
- U.S.: Vacancy is 6.8%, down 20 bps from year-end 2025 and the lowest since year-end 2024. Average asking rent is $10.40/sq ft, up 4.0% year over year.
See Cushman & Wakefield's Q3 2026 U.S. industrial vacancy and rent chart
- Dallas/Fort Worth: Vacancy fell 70 bps on the quarter and 150 bps on the year to 7.3%. Asking rent hit a record $9.76/sq ft (net), up 5.9% on the quarter and 19.9% on the year.
See Cushman & Wakefield's Q3 2026 Dallas/Fort Worth vacancy and rent chart
- Charlotte: Vacancy rose 30 bps on the quarter to 7.8%. Overall asking rent slipped 0.6% on the quarter to $8.60/sq ft.
See Cushman & Wakefield's Q3 2026 Charlotte vacancy and rent chart
What it means
- Shippers & manufacturers
- National asking rent is up 4.0% to $10.40/sq ft (Q3 2026), and Dallas/Fort Worth rent is up 19.9%. Before you sign for overflow space, price flexible 3PL capacity against it.
- 3PLs & warehouse operators
- Markets are splitting: Dallas/Fort Worth vacancy fell to 7.3% while Charlotte rose to 7.8%. Renewal math now depends on the market, so output per square foot matters most where space is tightest.
Sources: Cushman & Wakefield U.S. Industrial MarketBeat, Dallas/Fort Worth, Charlotte
5. Freight
- Logistics Managers' Index (October): 70.7, up 0.5 from September's 70.2 (above 50 = expansion).
- Inventory levels: 66.9 (+8.0), the fastest expansion since September 2022
- Warehousing capacity: 43.5, still contracting
- Warehousing prices: 80.7 (+7.2), the fastest growth since May 2022
- Transportation prices: 88.0 (−4.7)
- Transportation capacity: 38.0
See the LMI's warehousing capacity and prices charts in the October 2026 report
- Cass Freight Index (September): Shipments +1.9% year over year and +2.3% from August. Expenditures +20.4% year over year.
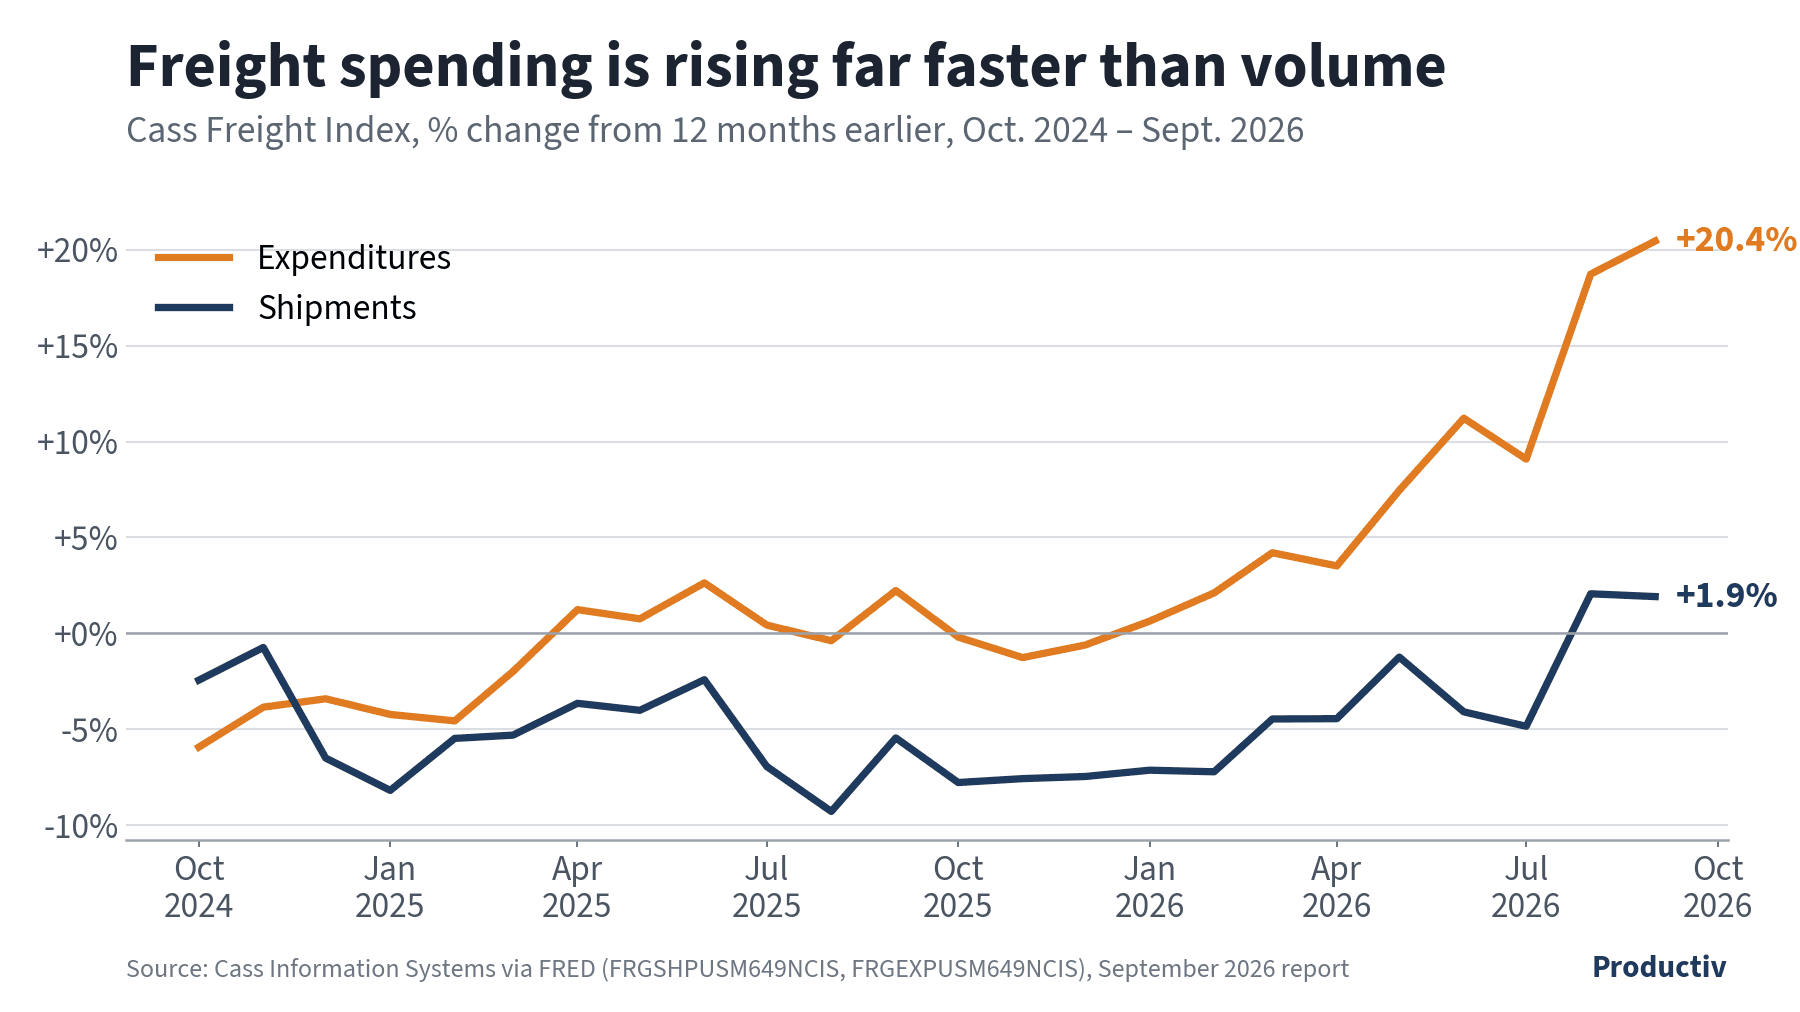
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/07-cass.csv
Chart data (table)
| Month | Shipments | Expenditures |
|---|---|---|
| Oct. 2024 | -2.4% | -5.9% |
| Nov. 2024 | -0.7% | -3.8% |
| Dec. 2024 | -6.5% | -3.4% |
| Jan. 2025 | -8.2% | -4.2% |
| Feb. 2025 | -5.5% | -4.6% |
| March 2025 | -5.3% | -2.0% |
| April 2025 | -3.6% | +1.2% |
| May 2025 | -4.0% | +0.8% |
| June 2025 | -2.4% | +2.6% |
| July 2025 | -6.9% | +0.4% |
| Aug. 2025 | -9.3% | -0.4% |
| Sept. 2025 | -5.4% | +2.2% |
| Oct. 2025 | -7.8% | -0.2% |
| Nov. 2025 | -7.6% | -1.3% |
| Dec. 2025 | -7.5% | -0.6% |
| Jan. 2026 | -7.1% | +0.6% |
| Feb. 2026 | -7.2% | +2.1% |
| March 2026 | -4.5% | +4.2% |
| April 2026 | -4.4% | +3.5% |
| May 2026 | -1.2% | +7.5% |
| June 2026 | -4.1% | +11.2% |
| July 2026 | -4.8% | +9.1% |
| Aug. 2026 | +2.1% | +18.7% |
| Sept. 2026 | +1.9% | +20.4% |
- Diesel (EIA): $6.292/gal for the week of Nov. 2. That's down 6.0¢ on the week but up $2.539 (68%) from a year ago.
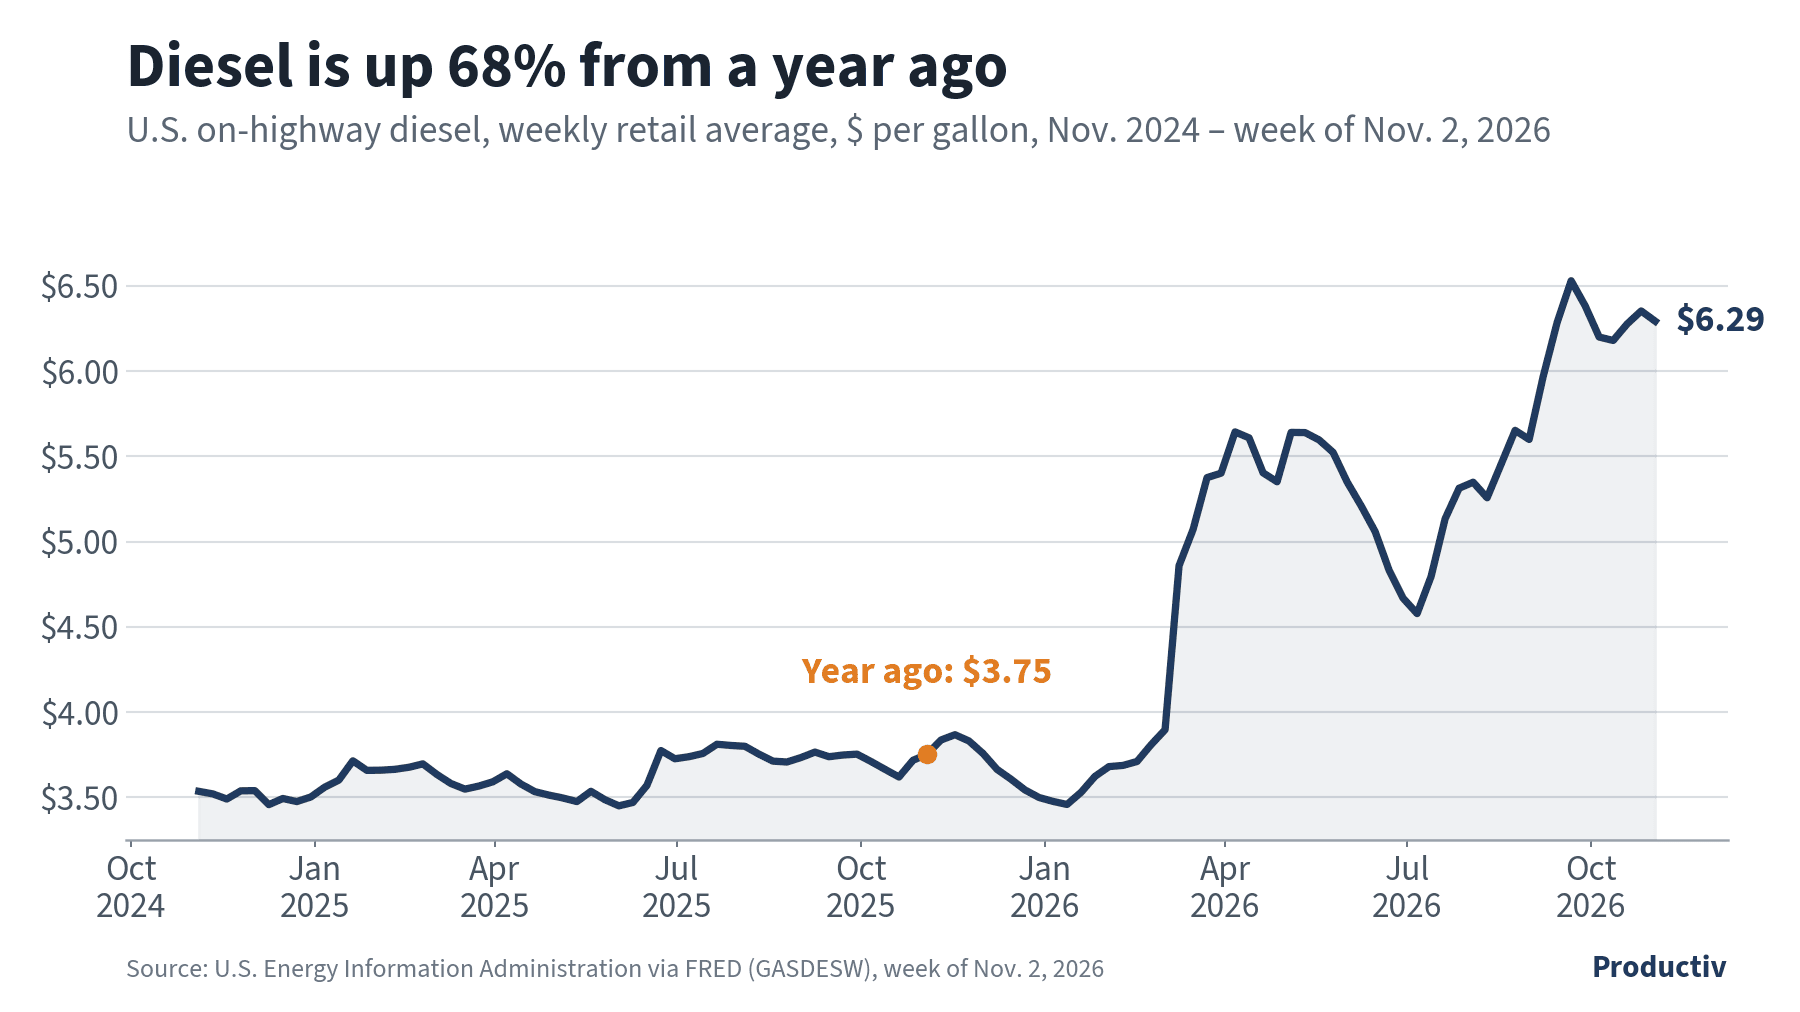
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/06-diesel.csv
Chart data (table)
| Week of | Diesel ($/gal) |
|---|---|
| Nov. 25, 2024 | $3.539 |
| Dec. 30, 2024 | $3.503 |
| Jan. 27, 2025 | $3.659 |
| Feb. 24, 2025 | $3.697 |
| March 31, 2025 | $3.592 |
| April 28, 2025 | $3.514 |
| May 26, 2025 | $3.487 |
| June 30, 2025 | $3.727 |
| July 28, 2025 | $3.805 |
| Aug. 25, 2025 | $3.708 |
| Sept. 29, 2025 | $3.754 |
| Oct. 27, 2025 | $3.718 |
| Nov. 24, 2025 | $3.831 |
| Dec. 29, 2025 | $3.500 |
| Jan. 26, 2026 | $3.624 |
| Feb. 23, 2026 | $3.809 |
| March 30, 2026 | $5.401 |
| April 27, 2026 | $5.351 |
| May 25, 2026 | $5.523 |
| June 29, 2026 | $4.668 |
| July 27, 2026 | $5.313 |
| Aug. 31, 2026 | $5.599 |
| Sept. 28, 2026 | $6.382 |
| Oct. 26, 2026 | $6.352 |
| Nov. 2, 2026 | $6.292 |
Year-ago comparison: $3.753 for the week of Nov. 3, 2025. The download has every weekly reading.
Download CSV Data- DAT dry van (linehaul, excluding fuel): Spot averaged $2.23/mile for the week ending Oct. 31, +32.6% year over year. In September, contract averaged $2.40 against $2.17 spot.
See DAT's dry van spot rate chart in its Nov. 2 report
- Truckload pricing: The BLS producer price index for long-distance truckload was up 17.9% year over year in September (released Oct. 15). The Cass Truckload Linehaul Index was up 10.1%.
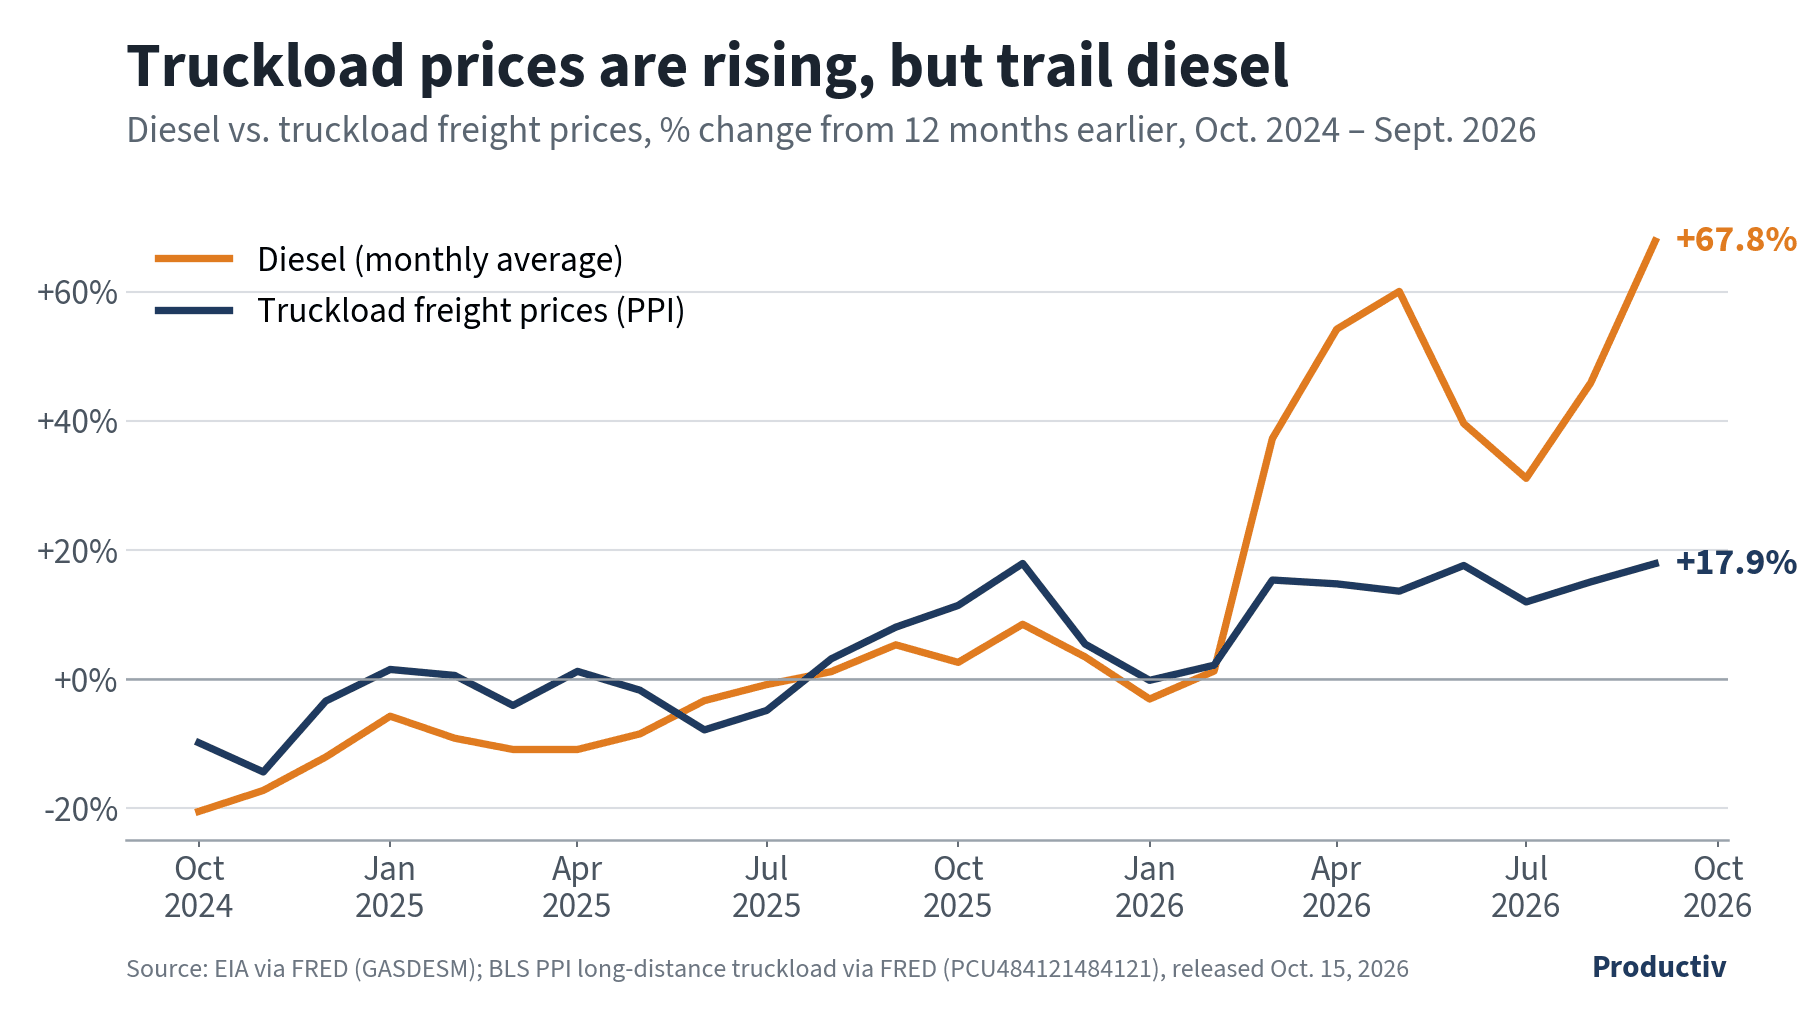
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/13-diesel-vs-truckload.csv
Chart data (table)
| Month | Diesel (monthly average) | Truckload freight prices (PPI) |
|---|---|---|
| Oct. 2024 | -20.5% | -9.8% |
| Nov. 2024 | -17.2% | -14.3% |
| Dec. 2024 | -12.0% | -3.4% |
| Jan. 2025 | -5.7% | +1.5% |
| Feb. 2025 | -9.1% | +0.6% |
| March 2025 | -10.9% | -4.0% |
| April 2025 | -10.9% | +1.2% |
| May 2025 | -8.5% | -1.7% |
| June 2025 | -3.3% | -7.8% |
| July 2025 | -0.8% | -4.8% |
| Aug. 2025 | +1.2% | +3.2% |
| Sept. 2025 | +5.3% | +8.1% |
| Oct. 2025 | +2.6% | +11.4% |
| Nov. 2025 | +8.5% | +17.9% |
| Dec. 2025 | +3.5% | +5.5% |
| Jan. 2026 | -3.1% | -0.2% |
| Feb. 2026 | +1.3% | +2.2% |
| March 2026 | +37.3% | +15.4% |
| April 2026 | +54.2% | +14.8% |
| May 2026 | +60.0% | +13.6% |
| June 2026 | +39.6% | +17.6% |
| July 2026 | +31.1% | +12.0% |
| Aug. 2026 | +45.9% | +15.1% |
| Sept. 2026 | +67.8% | +17.9% |
Recent truckload PPI months are preliminary.
Download CSV DataWhat it means
- Shippers & manufacturers
- Cass expenditures are up 20.4% on shipments up 1.9% (September). Freight cost is running far ahead of volume, so budget 2027 freight on cost, not on unit growth.
- 3PLs & warehouse operators
- Warehousing prices are at 80.7 and capacity is contracting at 43.5 (LMI, October). Customers will feel storage costs before peak ends; tell them now what is coming and why.
- Transportation & fleets
- Diesel is $6.292/gal (week of Nov. 2), up 68%, while DAT dry van spot is $2.23/mile, up 32.6%. Keep fuel surcharge tables current; revenue is rising, but fuel is rising faster.
Sources: LMI October 2026, Cass Transportation Index, September 2026, EIA Gasoline & Diesel Update, DAT Dry Van Report, Nov. 2, DAT September rates, BLS PPI truckload via FRED
6. Parcel
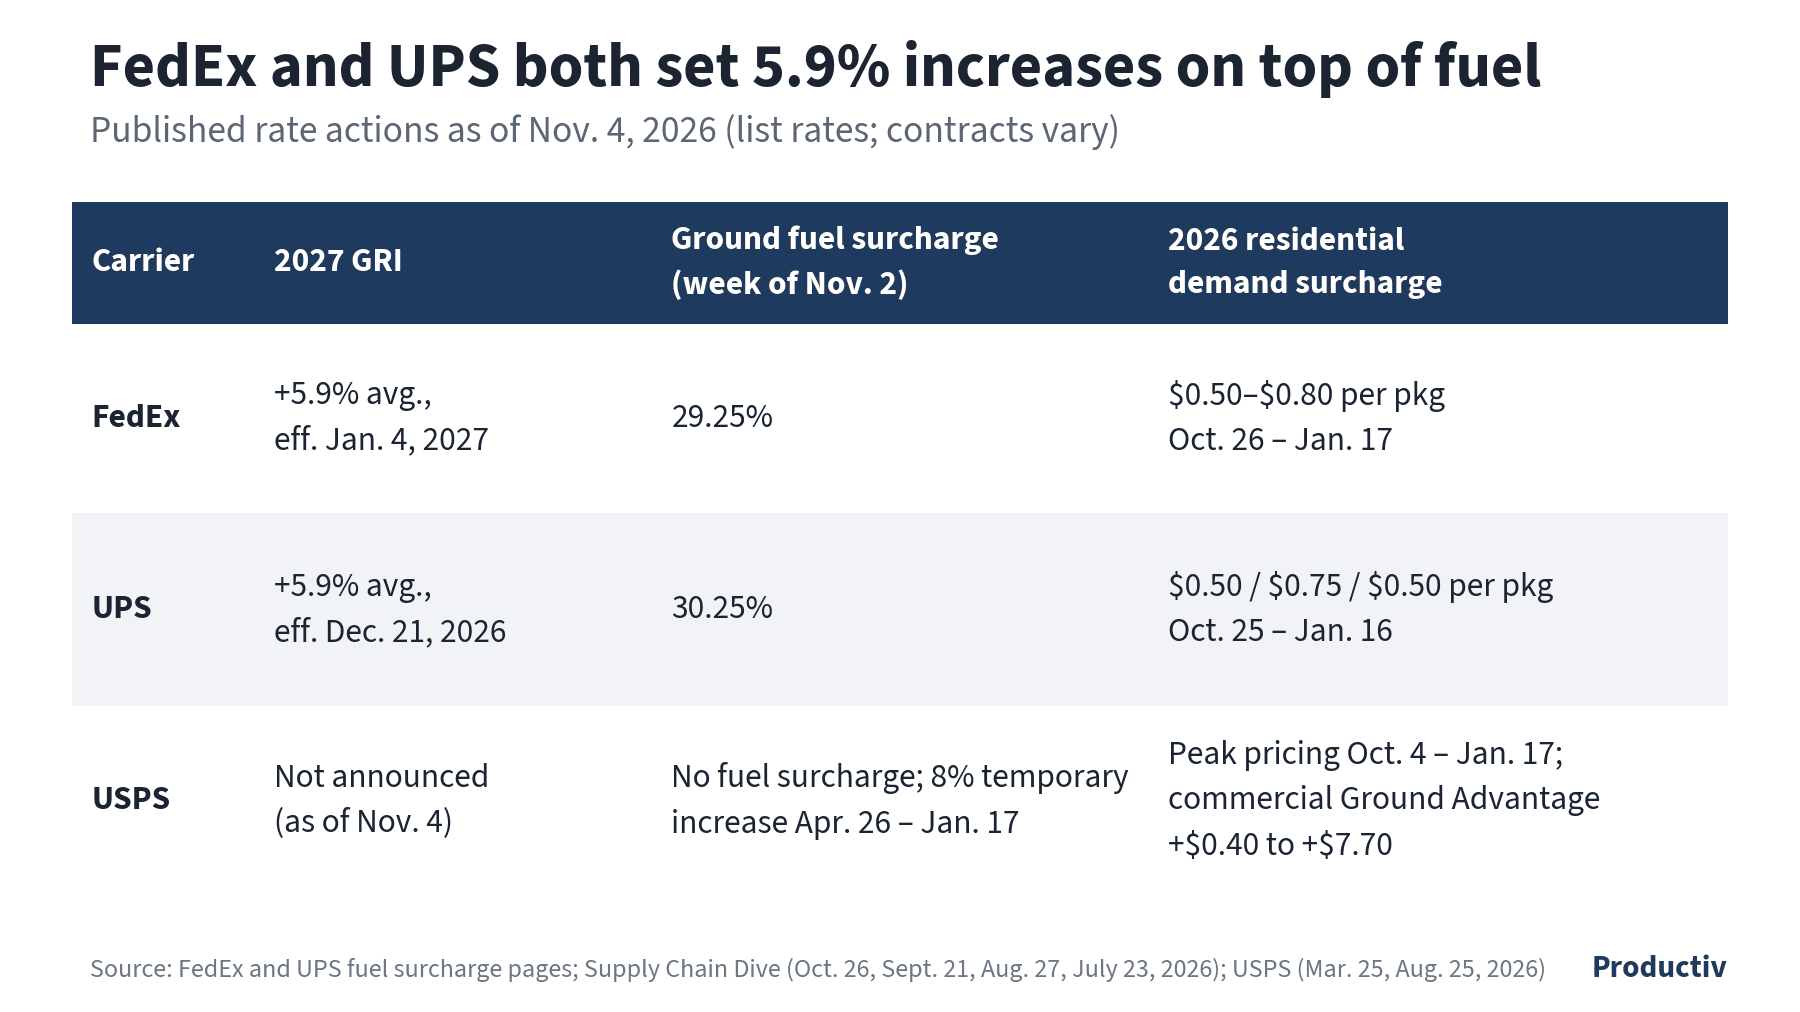
Data table and CSV: getproductiv.com/data/labor-logistics-indicators/2026-11/14-parcel-table.csv
Chart data (table)
| Carrier | 2027 GRI | Ground fuel surcharge (week of Nov. 2) | 2026 residential demand surcharge |
|---|---|---|---|
| FedEx | +5.9% avg., effective Jan. 4, 2027 | 29.25% | $0.50–$0.80 per package, Oct. 26 – Jan. 17 |
| UPS | +5.9% avg., effective Dec. 21, 2026 | 30.25% | $0.50 / $0.75 / $0.50 per package, Oct. 25 – Jan. 16 |
| USPS | Not announced (as of Nov. 4) | No fuel surcharge; 8% temporary increase Apr. 26 – Jan. 17 | Peak pricing Oct. 4 – Jan. 17; commercial Ground Advantage +$0.40 to +$7.70 |
2027 general rate increases
- UPS: Average +5.9% on daily ground, air and international rates, effective Dec. 21, 2026, in the middle of peak. Small-business rates rise 4.5%. The minimum billable weight for Additional Handling packages rises from 40 to 50 pounds.
- FedEx: Average +5.9%, effective Jan. 4, 2027.
- USPS: No January 2027 shipping price change found as of Nov. 4.
Fuel surcharges (week of Nov. 2)
- FedEx: Ground 29.25%. Express 33.25%.
- UPS: Ground 30.25%. Domestic Air 34.25%, up from 33.00% the week before.
- USPS: No separate fuel surcharge. An 8% time-limited increase on competitive parcels runs April 26, 2026 through Jan. 17, 2027.
2026 peak and demand surcharges
- UPS: Ground Residential is $0.50 through Nov. 21, then $0.75 (Nov. 22 to Dec. 26), then $0.50 through Jan. 16. Additional Handling runs $8.75 to $11.90.
- FedEx: Ground/Home Delivery residential is $0.50 to $0.80 from Oct. 26 to Jan. 17. Additional Handling runs $8.80 to $11.85.
- USPS: Peak pricing runs Oct. 4 to Jan. 17. For commercial Ground Advantage, it adds $0.40 (Zones 1–4, 0–3 lb) up to $7.70 (Zones 5–9, 26–70 lb).
What it means
- Shippers & manufacturers
- UPS's 5.9% increase lands Dec. 21, before peak ends, on top of a 30.25% ground fuel surcharge and the $0.75 residential peak fee. Rate-shop between carriers for late-December volume.
- 3PLs & warehouse operators
- UPS raises the Additional Handling billable minimum to 50 pounds on Dec. 21, and Additional Handling already runs $8.75 to $11.90 per package. Carton selection is a margin decision. Our peak readiness checklist covers where those costs hide.
Sources: Supply Chain Dive: UPS 2027 rates, Supply Chain Dive: FedEx 2027 rates, FedEx fuel surcharge, UPS fuel surcharge, Supply Chain Dive: UPS peak, Supply Chain Dive: FedEx peak, USPS peak pricing, USPS 8% increase
The Ecosystem Breakdown
One key indicator from each section, and which way it cuts for shippers, 3PLs and fleets this month.
| Indicator | Latest value | Change | Shippers & manufacturers | 3PLs & warehouses | Transportation & fleets |
|---|---|---|---|---|---|
| EconomyPPI, final demand | +6.3% y/y (Sept. 2026, BLS) | +1.3% m/m; core +5.0% y/y | HeadwindPackaging and component costs still climbing | HeadwindSupply costs up; check pass-through clauses | NeutralTruckload prices tracked under Freight |
| Credit & Rates10-year Treasury | 4.91% (Nov. 2, 2026, FRED) | From 5.24% on Oct. 1; Fed held at 3.75%–4.00% | NeutralCarrying inventory still costly, a bit less than in October | NeutralPrime rate unchanged at 7.00% | NeutralEquipment financing unchanged |
| LaborWarehousing & storage employment | 1,831,800 (Sept. 2026, prelim., BLS) | −21,600 y/y; pay +3.1% vs. CPI +3.7% | NeutralHeadcount is not the binding constraint | HeadwindReal pay is falling; retention costs rise | NeutralQuits rate eased to 2.1% (T/W/U) |
| Industrial Real EstateU.S. industrial vacancy | 6.8% (Q3 2026, Cushman & Wakefield) | −20 bps vs. year-end 2025; rent $10.40/sq ft, +4.0% y/y | HeadwindLease costs still rising; price flexible capacity | HeadwindDallas/Fort Worth rent +19.9% y/y | NeutralNo direct effect |
| FreightU.S. on-highway diesel | $6.292/gal (week of Nov. 2, 2026, EIA) | +$2.539 y/y; −6.0¢ w/w | HeadwindFuel in every freight bill | HeadwindInbound and outbound freight costs up | HeadwindFuel cost up; dry van spot +32.6% y/y helps revenue |
| ParcelUPS ground fuel surcharge | 30.25% (week of Nov. 2, 2026) | UPS and FedEx 2027 GRIs +5.9% avg. | HeadwindBase rates and fuel both rising | NeutralPack-out and carton size set surcharge exposure | NeutralNo direct effect |
Deep dive: inventory is outrunning storage
The October LMI points to one problem. Inventory levels jumped 8.0 points to 66.9, the fastest expansion since September 2022. Warehousing capacity contracted at 43.5. Warehousing prices rose to 80.7, the fastest growth since May 2022. More goods are arriving than the available space can absorb, and the price of space is moving first.
The lease market shows the same thing, unevenly. National vacancy fell to 6.8% in Q3, its lowest since year-end 2024, and asking rent rose 4.0% on the year to $10.40/sq ft. Dallas/Fort Worth tightened sharply: vacancy fell to 7.3% and asking rent hit a record $9.76, up 19.9% on the year. Charlotte went the other way, with vacancy up to 7.8% and rent down 0.6% on the quarter. A single national rent assumption will be wrong in both directions.
Holding inventory also costs more than it did a year ago. The 10-year Treasury is 4.91% (Nov. 2), against 4.13% a year earlier, and the prime rate is 7.00%. Units that sit in overflow space through January carry both the higher rent and the higher cost of money.
The way out of a space squeeze is usually speed, not square feet. Inventory that turns faster needs less room. That depends on receiving that clears docks the same day, slotting that keeps fast movers near pack-out, and kitting and display builds finished close to ship date instead of weeks ahead. It also depends on parcel. UPS's billable minimum for Additional Handling rises to 50 pounds on Dec. 21, so oversized cartons cost space on the way in and money on the way out.
For manufacturers, the same pressure shows up inside the plant. ISM new orders are 55.5, and factories that stage finished goods for weeks before shipping are using space they now pay more for. Whether finishing work runs in a 3PL building or inside the client's plant, the operations that ship what they build sooner will need less space this peak.
Operational directives
Optimize: space and flow
- Measure dwell time by SKU weekly through January and move slow movers out of prime pick space first.
- Build kits and displays closer to ship date. With warehousing prices at 80.7 on the LMI, finished goods sitting early are a cost, not a buffer.
- Price overflow options now. Dallas/Fort Worth asking rent is up 19.9%; short-term 3PL capacity can cost less than a lease you only need for a quarter.
Safeguard: parcel and compliance cost
- Audit carton sizes against UPS's new 50-pound Additional Handling minimum before Dec. 21.
- Check routing guide and ASN/EDI accuracy now. A chargeback in December comes with a reship at peak fuel and peak surcharge rates.
- Keep trained leads on labeling and compliance-critical stations; quits are low, so hold on to the people you have.
Synchronize: production and regional fulfillment
- With diesel at $6.292/gal and truckload producer prices up 17.9%, move finished goods to regional fulfillment in planned full loads rather than expedited partials.
- Time production runs to fulfillment windows so inventory arrives when there is room to store and ship it.
- Ship December volume before Dec. 21 where you can, ahead of UPS's 5.9% increase.
What's next
The October jobs report comes out Nov. 6. October CPI and the weekly EIA diesel update follow on Nov. 10, and October PPI on Nov. 13. The Census Bureau publishes Q3 e-commerce on Nov. 19, and the Q3 GDP second estimate is due Nov. 25. October JOLTS arrives Dec. 1, and the Fed meets Dec. 8–9. Our next issue arrives in early December.
Monthly · Free
Get Labor & Logistics Indicators every month
Our read on the numbers that shape warehouse labor, fulfillment and freight, in your inbox once a month.
Get the next issue and the full data: every chart's data table and CSV, and the monthly email sign-up, are at getproductiv.com/insights/labor-logistics-indicators.
If peak surcharges are changing your fulfillment math, talk to our team (getproductiv.com/contact).
About this report and methodology
Labor & Logistics Indicators is published monthly by Productiv. It is built from official public data (BEA, BLS, the Federal Reserve, Freddie Mac, EIA, FRED and the Census Bureau) and named industry sources (Cushman & Wakefield, the Logistics Managers' Index, DAT, Cass, ISM, UPS, FedEx and USPS). Every figure is linked to its source with its reference period and release date. It contains no proprietary Productiv data.
How figures are calculated: year-over-year and month-over-month changes are taken from the official series as published. Our charts plot about 24 months of published data without estimates or seasonal adjustments of our own. Third-party charts are linked, not reproduced.
The Productiv Labor & Logistics Pressure Index is different: it is a Productiv calculation from public data, not a figure as published by a source (see the methodology). Each issue recomputes its full history. If a month we have already published moves by 1 point or more, we note it in a footnote in the new issue; past issues are not edited.
Revisions: when a source revises a figure, we update it on this page, change the “Updated” date and note what changed. Past issues keep their URLs.
Productiv, Inc. is headquartered in Midlothian, Virginia. It runs 3PL fulfillment in Dallas and Charlotte, and onsite kitting and co-packing teams inside client plants in Richmond, Charlotte, Raleigh, Dallas and Salt Lake City.
Cite as: Productiv, Labor & Logistics Indicators, November 2026, https://getproductiv.com/insights/labor-logistics-indicators/2026-11